NVDA Bleeds 10% in 2 Sessions as Washington Circles Jensen Huang, but a $108B Quarter Keeps a $200 Price Target
Nvidia trades at $167, just above its $164 yearly low and 31% under its $243.37 peak | That's TradingNEWS
Key Points
- Nvidia dropped to $167.02, down 6.52% after Monday’s 4.27% loss, sitting less than $3 above its $164.27 52-week low.
- Q2 revenue hit $96.22 billion, up 106%, with Q3 guided to $108.0 billion and the stock at 21 times forward earnings.
- Support at $164.27 guards $150; a daily close above $186.64 fills the gap and opens the $200 upside target.
Nvidia (NASDAQ:NVDA) extended Monday’s loss on Tuesday. The stock dropped as much as 6.5% and traded at $167.02 by mid-session, down $11.65 from Monday’s $178.67 close. Monday had already cost 4.27%, with the stock off as much as 8% intraday. In two sessions, the chipmaker that led this AI cycle has lost $19.62 a share from Friday’s close near $186.64. That is a two-day drop of more than 10%, and it leaves the stock just above its 52-week low of $164.27.
From the 52-week high of $243.37, the decline now runs past 31%. At $167.02 and about 24.9 billion shares outstanding, Nvidia’s market value is down to $4.2 trillion. On October 14, when the stock closed at $221.30, it was worth $5.51 trillion. More than $1.3 trillion of value has come off in under four weeks, and the last two sessions account for a large share of that.
What stands out is how the rest of the market traded around Nvidia. On Monday the Philadelphia Semiconductor Index jumped 7% and reclaimed 10,000. AMD ripped more than 13%. The Nasdaq Composite rose 2.74% to 25,253.14, and roughly three quarters of listed companies finished higher. Nvidia fell 4.27% in the middle of that rally. It was the stock’s worst relative showing during a 5%-plus chip rally since October. For two years the index moved with Nvidia. This week it moved without it.
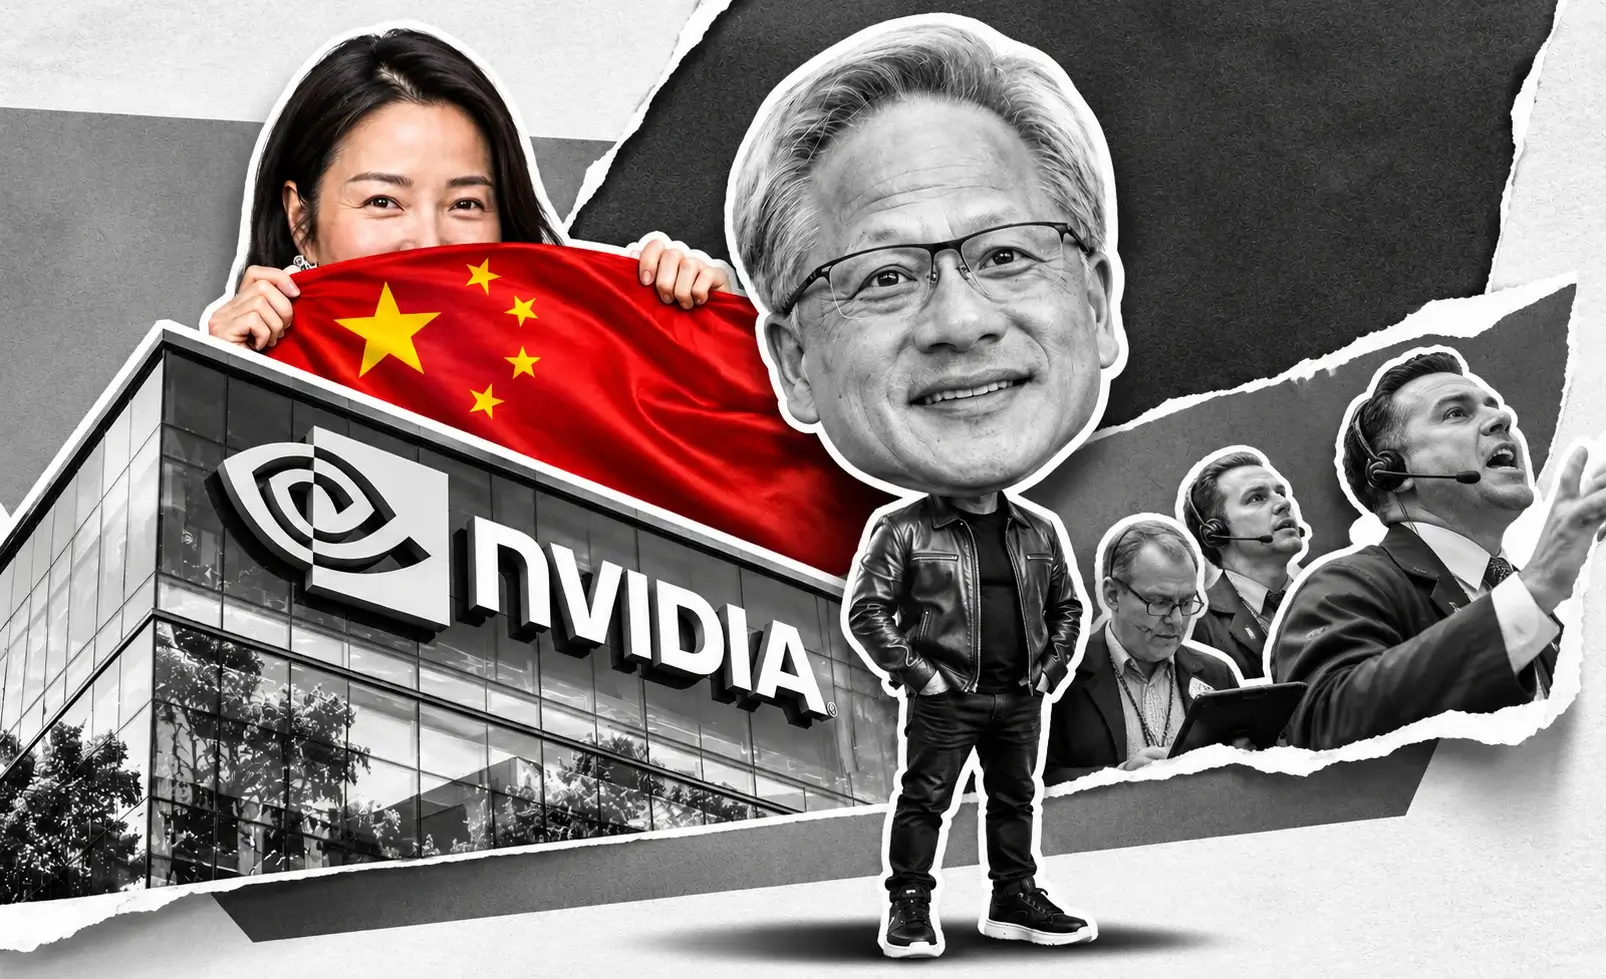
On Tuesday the broad market turned lower after the hot October CPI. The Nasdaq lost 0.87% to 25,034.07 and the S&P 500 fell 0.71% to 7,496.17. Even so, Nvidia’s loss was several times the index decline, while most of the chip group held up. The selling is specific to Nvidia and specific to one story: the board investigation into CEO Jensen Huang’s relationship with a woman US intelligence officials suspect of spying for China, and the political and regulatory pressure that has built around it.
The tape is telling traders that the market has started to price key-person risk, governance risk and export-control risk into a stock that, a week before earnings, had been trading almost purely on demand for its data center products. That is a new kind of discount for Nvidia, and it explains why a company guiding to $108 billion of quarterly revenue is trading at the bottom of its yearly range.
The Board Investigation and What It Covers
The trigger came over the weekend. On Sunday, November 8, Huang sent employees an email admitting to an extramarital affair. The relationship was with Alice Huang, also known as Huang Le, a former executive at Singapore-based data center company Megaspeed. The two are not related. US intelligence assessments, as reported, concluded that she was passing information to Chinese intelligence and that the Nvidia CEO was viewed as a potential target of that effort. In the email Huang apologized to his family, colleagues, board, partners and shareholders. He said he takes full responsibility and that leading the company remains the privilege of his life.
The same day, Nvidia’s board announced an independent investigation. A committee of independent directors, assisted by outside independent counsel, will run it. The board said it has no reason to believe either national security or company secrets were compromised, but that the inquiry will examine all available information. It also said Huang fully supports the review, has committed to cooperating, and that the board has confidence in him and his leadership team. A company spokesman said Huang will continue to lead as CEO without interruption. Nvidia’s filings and statements are on its SEC filing page.
China’s foreign ministry has called the spying allegation unsubstantiated and groundless. The intelligence claims have not been independently confirmed in public, and Alice Huang has not responded to requests for comment. None of that has steadied the stock, because the investigation’s scope reaches past the personal matter.
The probe could look at prior public statements. In October, after earlier reports linked the two, Huang said on the record that their interactions were related to Megaspeed and were completely normal. The admission now sits next to that statement. If the board concludes that earlier statements by the CEO or company spokespeople were inaccurate, the questions shift from personal conduct to disclosure, and disclosure is a far more serious problem for a public company.
The key question for shareholders is whether Huang stays in the job. He co-founded the company in 1993 and has run it ever since. There is no obvious successor on the management bench with his standing among customers, suppliers and policymakers. The market has attached a valuation figure to that risk: estimates circulating Tuesday put Nvidia’s value at almost 30% lower if Huang were no longer CEO. That number is a sentiment gauge, not a calculation. But it shows why investors are treating the board review as a binary event with a wide range of outcomes.
The board has not set a timeline. Until it reports, every new headline about the investigation will hit the stock, and there are several scheduled events in the next eight days that will produce those headlines.
Megaspeed, Malaysia and the Export-Control Thread
The personal story would matter less if it were not tied to chip flows into China. Megaspeed was founded in 2023 when the overseas operations of Chinese gaming and cloud company 7Road moved to Singapore and were renamed. 7Road counts China’s central government and several local governments among its owners. Alice Huang was listed as Megaspeed’s managing director for its first eight months. She left the company in recent months.
US authorities began looking at Megaspeed in 2024 over suspected circumvention of export controls. The Commerce Department ran the early inquiry and the Justice Department later joined. The company built data centers and rented computing capacity, and reports have tied its customers to Chinese firms including Alibaba. Megaspeed did not buy directly from Nvidia. It bought systems through Aivres Systems, the California-based US subsidiary of Chinese server maker Inspur. Because Aivres records sales as a US company, it could buy Nvidia chips freely.
The hardware went to Megaspeed’s Malaysian subsidiary, Speedmatrix. Earlier reports said Megaspeed bought about $2 billion of Nvidia’s most advanced chips, roughly $1 billion in the first three months after a June 2024 meeting in Taipei and another $1 billion over the following nine months. Trade data reviewed later showed a Megaspeed-linked company in Malaysia acquired at least $4.8 billion of Nvidia technology equipment from June 2024 to February 2026. On Tuesday a fresh report put the China-bound chip flow tied to her network at $7.5 billion. That figure hit the stock in the late morning.
Nvidia has said repeatedly that it found no evidence its chips were diverted to China through Megaspeed, and that customers like Megaspeed receive ordinary business information with nothing relevant to national security. Megaspeed stopped all Nvidia hardware orders in mid-2025. Further systems worth more than $3 billion had been planned before the investigations began.
The export issue is where the financial risk sits. The Bureau of Industry and Security has blocked successive generations of Nvidia data center chips for Chinese buyers since 2022. Nvidia’s Q3 guidance already assumes zero data center compute revenue from China, and Hopper shipments to China were below 1% of data center revenue last quarter. So the revenue exposure is small. The exposure that matters is regulatory: penalties, tighter licensing for Southeast Asian customers, and slower approvals for shipments to markets that have become important for growth. Any of those would hit the non-China business, which is the entire guidance.
Washington Turns Up the Pressure After the Midterms
The political setting changed sharply in the past week. The midterms handed Democrats both chambers of Congress. Senator Elizabeth Warren is expected to chair the Senate Banking Committee from January 2027, and she has already moved on Nvidia. On October 29 she urged Huang and the board to give Congress answers on the Megaspeed reports.
Separately, Warren and Republican Senator Jim Banks, both on the Banking Committee, wrote to Commerce Secretary Howard Lutnick. They asked him to determine whether statements and certifications by Nvidia’s leadership to federal officials and the public about the absence of chip diversion were materially false or misleading. That letter followed Justice Department charges against three men tied to Nvidia customer Super Micro Computer, who are accused of smuggling billions of dollars of AI servers into China. A bipartisan request on the accuracy of company representations is a different level of risk from a partisan press release.
The House has moved too. In a letter dated November 4, the chairs of the House Foreign Affairs Committee and the Permanent Select Committee on Intelligence asked Huang to appear behind closed doors on November 18 to discuss his interactions with the alleged Chinese asset and Nvidia’s security protocols. The letter went out the day after Republicans lost control of Congress. Nvidia has pushed back on the request and has not said whether Huang will attend.
The calendar overlap is ugly for the stock. Nvidia reports fiscal Q3 results on November 17 after the close. The requested closed-door session is the next day. The Fed minutes land on November 18 as well. Whatever the earnings show, the stock will trade through a congressional event within 24 hours of the print.
There is also a policy angle that goes beyond Huang. Several bills before Congress would limit AI chip exports to China and add oversight of how licenses are granted. Huang has lobbied the administration to ease restrictions and has argued that keeping American technology in the Chinese market strengthens the US. With his credibility now under review, that argument is harder to make. Federal investigators are preparing to examine the matter as well, and Democrats with new committee gavels have every incentive to keep it in the news. For a stock priced on a long runway of AI spending, more uncertainty in Washington means a higher discount rate.
Q2 Fiscal 2027: The Numbers the Market Is Ignoring
Set the governance story aside and the operating picture is the strongest in the semiconductor industry. In its second-quarter fiscal 2027 release on August 26, Nvidia reported revenue of $96.22 billion for the quarter ended July 26. That was up 106% from $46.7 billion a year earlier and 18% from the April quarter, and it beat the company’s own May guidance midpoint of $91 billion by 5.7%.
Data Center revenue reached a record $89.0 billion, up 117% year over year and 18% sequentially, or 92.5% of total sales. Hyperscale revenue more than doubled from a year ago and rose 13% sequentially. The segment covering AI natives, enterprises and sovereign customers grew 138%. Edge Computing added $7.2 billion, up 27%. Data center networking also rose 138%, which shows the build-out extends into switching and interconnect, not only GPUs.
Profitability expanded. GAAP gross margin was 75.0% against 72.4% a year earlier, a gain of 260 basis points. Operating income jumped 124% to $63.7 billion, a GAAP operating margin of 66.2%. Net income rose 126% to $59.7 billion. GAAP diluted EPS was $2.46 and non-GAAP EPS was $2.22, against $1.05 a year earlier. Free cash flow came in at $21.3 billion, up from $13.5 billion.
Nvidia returned about $26 billion to shareholders through buybacks and dividends during the quarter and ended it with $99 billion left on its repurchase authorization. That gives the company a lot of firepower to support the stock at depressed prices, though buyback timing around an open board investigation is a judgment call the company has to make carefully.
The market loved the print at the time. Shares fell in after-hours trading, then closed August 27 at $227.98, up 8.74%, adding $441.5 billion of market value in a single session. That was the second-largest one-day gain in US market history. The stock has since given up all of that and another $60 on top. Business momentum has not reversed in that period. The discount comes from risk the market has added on, not from any loss of earnings power that has shown up so far.
Q3 Guidance and the November 17 Setup
Nvidia reports fiscal Q3 2027 on Tuesday, November 17, for the quarter ended October 25. CFO Colette Kress will post written commentary at about 1:20 p.m. Pacific, and the call starts at 2:00 p.m. Pacific, 5:00 p.m. Eastern. The report lands a day earlier in the week than the company’s usual schedule.
The company guided Q3 revenue to $108.0 billion, plus or minus 2%. That is a range of $105.84 billion to $110.16 billion and a 12% sequential increase at the midpoint. Gross margin is guided at 74.0%, plus or minus 50 basis points, with GAAP operating expenses of $9.2 billion and non-GAAP of $9.0 billion. The guide assumes no data center compute revenue from China. Consensus sits at $2.47 of EPS on revenue of $108.8 billion to $109.0 billion, just above the guidance midpoint. Nvidia has beaten on revenue and adjusted EPS for five straight quarters.
The quarter itself is unlikely to be the problem. The Vera Rubin platform is in full production, with racks running at hyperscalers and cloud providers, and was expected to account for about 20% of data center revenue. In August, Kress also signaled that fiscal 2028 revenue, which corresponds to calendar 2027, could grow about 70%, far above the 44% the market was modeling at the time. A reaffirmation of that framework would be the single most important number on the call.
The risk sits in guidance and commentary. The company expects gross margin to trough in the 71% to 72% range in Q4 because of rising memory costs. Nvidia raised its supplier purchase commitments from $119 billion to $279 billion, mostly memory for Vera Rubin production. Kress has warned that pricing conditions will stay extreme and that supply could limit growth through the end of fiscal 2028. A soft Q4 margin guide combined with a governance overhang would hit the stock hard.
Then there is the call itself. Analysts will ask about the board investigation, and management’s answers will move the stock as much as the numbers. A clear statement on scope, timing and Huang’s role would remove some of the discount. A non-answer would extend it. The options market is pricing a wide move, and the move this time will depend on more than revenue.
Valuation at 21 Times Forward Earnings
At $167.02, Nvidia trades at about 21 times forward earnings. Before the scandal broke, at $172 earlier on Tuesday, the multiple was about 22 times. For a company growing revenue at 106% with a 66% operating margin, that is a low multiple by any growth-adjusted measure. It is close to the market multiple for the S&P 500, which is growing earnings at a fraction of Nvidia’s pace.
The math is simple. Annualize the Q3 guidance midpoint and Nvidia is running at $432 billion of revenue. Apply even a reduced 70% net margin and that is more than $300 billion of annual earnings power at the current run rate, against a $4.2 trillion market value. If calendar 2027 revenue really grows 70%, the forward multiple on next year’s earnings drops into the low teens. Those numbers do not make the stock cheap by default, but they show how much fear is already in the price.
The multiple compression started well before the scandal. The stock had gained just 2.6% for the year by late October and was 18% below its May peak, while the semiconductor index nearly doubled over six months. Institutional flows went elsewhere. Money moved into memory makers, with Micron posting record revenue of $41.46 billion, up 346%, and HBM production sold out. Twenty-day money-flow readings for Nvidia were the weakest among the large chip names before the weekend news. That is the context for this week’s fall: the stock was already under distribution, and the scandal gave holders another reason to sell.
There is a case for a discount beyond the personal story. Nvidia’s commitments to AI cloud partners, including lease guarantees, have climbed toward an estimated $165 billion. Those commitments turn the chipmaker into a partial financial backstop for customers that carry heavy debt. If AI cloud providers hit liquidity trouble, Nvidia’s exposure would be much larger than its receivables. Nvidia has also been spending heavily on equity stakes in partners and customers. It used more than $70 billion of cash on such deals last fiscal year, and critics have called some of those arrangements circular.
A 21 times multiple bakes in a lot of that risk already. The question for the target is how much of the remaining discount can be recovered after November 17 and after the board reports.
The Anthropic Placement and the Circular-Financing Debate
Tuesday also brought a reminder of how deeply Nvidia is tied into its customers’ balance sheets. Anthropic’s amended S-1, filed with the SEC on November 10, set out a $26.0 billion private placement alongside its IPO. Seven suppliers agreed to buy non-voting Class N common stock at the IPO price. Nvidia and Google committed $10.0 billion each, AMD $2.5 billion, Broadcom, Micron and Microsoft $1.0 billion each, and TSMC $500 million. Anthropic set an IPO price range of $70 to $78 and plans to sell 825 million shares on Nasdaq under the ticker ANT.
The placement is 2.9% of the $900.9 billion of computing and infrastructure commitments Anthropic disclosed in the filing. Seen one way, that is a supplier locking in a long-term relationship with one of the largest compute buyers in the world. Seen another way, it is a supplier helping finance the customer that buys its chips. That is the circular-financing critique that has followed Nvidia’s investments in OpenAI, CoreWeave and others.
For the stock, the $10 billion commitment is not material against $99 billion of buyback capacity and $21.3 billion of quarterly free cash flow. What matters is the pattern. When the market is calm, these deals read as smart capital allocation that protects share of wallet. When the market is nervous, as it is now, they read as balance-sheet risk layered on top of operating risk. Tuesday was a nervous day, and Nvidia lost more on the session than Google or Microsoft did.
Competition is also changing the conversation. Alphabet now sells its custom AI chips to third parties, including Oracle, and its software stack is making it easier for developers to run models across different accelerators. That chips away at CUDA, Nvidia’s biggest lock-in advantage. Meta has worked with competing chip vendors to avoid depending on a single supplier. The largest AI labs now buy from Nvidia, Google, AMD and Broadcom at once, and Anthropic’s placement roster shows exactly that. Nvidia remains the default buyer’s choice, but a market with multiple credible suppliers supports a lower multiple than one with a near-monopoly.
The Macro Layer: CPI, Yields and a Hawkish Fed
Nvidia’s fall on Tuesday came on a day the macro tape turned against long-duration growth stocks. The October CPI came in hot. Headline rose 0.4% against a 0.3% forecast, and core rose 0.3% against 0.2%. It was the third straight core reading at 0.3% and the fifth this year. Shelter rose 0.3%, food 0.5%, energy 0.7% and gasoline 1.0%. Used cars fell 1.2%.
Before the print, Fed Governor Christopher Waller said a 50bp hike should be considered if core runs around 0.3%. Dallas Fed President Lorie Logan called for two more hikes. Futures moved to 85% odds of a 25bp hike and 15% of a 50bp hike at the December 9 FOMC, up from zero odds of 50bp before the report. A 25bp move would take the federal funds range to 4.00%–4.25%. The November CPI arrives December 10, the day after the meeting.
Treasury yields jumped. The 2-year rose 19 basis points to 4.736%. The 10-year traded at 4.99% and the 30-year at 5.29%. The dollar index rose 0.3% to 102.00, and the VIX climbed to 21.06. That is a tough backdrop for any stock whose value depends on cash flows several years out. A 10-year yield near 5% compresses multiples across growth stocks, and Nvidia’s multiple is set by expectations for 2027 and 2028.
The good news for Nvidia bulls is that the macro hit is shared. AMD, Broadcom and the rest of the chip group took the same rate shock on Tuesday and held up better. That isolates the Nvidia-specific discount. If yields stabilize, the macro drag eases for the whole group, but Nvidia’s own risk premium stays until the board investigation produces an answer. The macro calendar is busy before earnings: PPI is due Friday, and the Fed minutes are due November 18. A firm PPI would add pressure on the rate side going into the November 17 print.
Read More
-
Yen Stalls at 160 Despite a 3% JGB and Tokyo Core CPI at 2.0% — Intervention Sits at 164, Friday's Payrolls Decide
02.09.2026 · TradingNEWS ArchiveEnergy
-
Rocketlab Slides to $54 as Neutron Slips to 2027 and the Q3 Loss Widens to $0.12 — Bulls Need $65
10.11.2026 · TradingNEWS ArchiveStocks
-
Ethereum Slides to $2,024 as Hot CPI Lifts Fed Hike Odds — Reclaiming $2,310 Is the Upside Target
10.11.2026 · TradingNEWS ArchiveCrypto
-
Brent Slides Below $90, 1st Time Since August, 24% Off Its $118 High — $100 Is the Upside Target
10.11.2026 · TradingNEWS ArchiveCommodities
-
S&P 500 Sinks to 7,496, Nasdaq and Dow Fall as Hot CPI Revives Half-Point Hike Bets; Bulls Need 7,650
10.11.2026 · TradingNEWS ArchiveMarkets
-
Pound Rolls Over at 1.3459 as US Inflation Revives the Dollar, but BoE Hawks Keep a 1.3520 Target Alive
10.11.2026 · TradingNEWS ArchiveForex
Daily Chart: $164.27 Is the Line in the Sand
The technical picture has deteriorated quickly. Nvidia broke below its 200-day moving average on November 2, before the scandal, and has not been back above it since. The stock has fallen from $221.30 on October 14 and $217.97 on October 27 to $167.02, a slide of more than $50 in under four weeks. The two-day drop of more than 10% came with heavy volume, and both sessions closed near their lows. That is distribution, not a shakeout.
The key support is the 52-week low at $164.27, less than $3 below Tuesday’s mid-session price. It is the floor of the yearly range and the level where buyers stepped in before. A clean break below $164.27 would put the stock at its lowest level in more than a year and expose the $160 round number. Below that, $150 is the next major support, the area where the stock based before the August earnings run.
Overhead resistance starts at Monday’s $178.67 close. Above that, Friday’s $186.64 close leaves a gap that will act as a magnet if the board investigation produces good news or if earnings land well. The $200 level is the big psychological pivot and the bottom of the trading range the stock held through most of October before the slide. Clearing $200 would reclaim the zone where the stock traded before the 200-day break and would be a strong signal that the scandal discount is fading. The $217.97–$221.30 zone from mid-to-late October sits above that, and the August 27 close at $227.98 caps the broader recovery case.
Momentum is deeply oversold after a 31% drawdown from the $243.37 high and a 10% two-day drop. Oversold conditions often produce sharp rebounds, and Nvidia has a hard catalyst seven sessions away. But oversold does not mean the selling is done. The pattern that matters is how the stock behaves at $164.27. A test that holds, with a bounce back above $170 on rising volume, would point to a base forming ahead of earnings. A close below $164.27 would mean sellers have overpowered the yearly low, and the stock would likely trade into the earnings report under heavy pressure.
Dividend, Buybacks and What Supports the Floor
Several factors can support the price at these levels. The first is the buyback. Nvidia had $99 billion left on its authorization at the end of Q2 and returned $26 billion in that quarter. At $167, the same dollar amount retires more shares than it did at $228. A board that is confident in the business has every reason to keep buying, and any disclosure in the Q3 release that repurchases picked up during October would signal that confidence.
The dividend is small. The next ex-dividend date is December 4 for a payment of $0.01 a share. It does not support the stock in any meaningful way, but it marks the next corporate-calendar date after earnings.
The second support is the order book. Nvidia and Amazon Web Services announced plans to deploy an additional 2 million Nvidia GPUs across AWS infrastructure in 2027 and 2028, mainly for agentic and physical AI workloads. Anthropic’s $900.9 billion in compute commitments, much of which flows to Nvidia hardware directly or through cloud providers, adds to that visibility. Supplier purchase commitments of $279 billion are a cost, but they also show how much product Nvidia expects to ship. Customers do not walk away from a supply-constrained market because of a CEO’s personal conduct.
The third support is the valuation itself. At 21 times forward earnings, the stock is priced closer to a mature large-cap than to a company with triple-digit growth. Long-only funds that sold out of Nvidia earlier in the year for valuation reasons now see a different picture. That kind of buyer tends to show up on tests of yearly lows, not on breakouts, which is why $164.27 matters so much this week.
The fourth factor is the board’s own statement. By saying it sees no reason to believe national security or company secrets were compromised, and by expressing confidence in Huang, the board has set a baseline. If the investigation confirms that baseline, a large part of the discount comes back quickly. If it does not, the stock has a lot further to fall. The board controls the timing, and the market will reward any clarity it provides.
Scenarios Into Earnings and the Huang Decision
Three paths stand out over the next two weeks. In the bull path, Nvidia beats the $108 billion guide on November 17, guides Q4 above consensus, holds the margin trough at 71% to 72% or better, and reaffirms the fiscal 2028 growth framework. Management also addresses the investigation clearly and Huang confirms he remains in the role. In that case the stock would fill the gap to $186.64 and push toward $200 within days. Short covering would add fuel, because the stock has been hit hard enough to attract fresh short sellers this week.
In the base path, the numbers are good but the investigation stays open, and Huang does not appear before the House committee on November 18 or appears with no public readout. The stock would likely bounce off $164.27 on the print and then stall between $178.67 and $186.64 while the market waits for the board’s findings. That would leave Nvidia in a wide, volatile range into December, with rallies sold and dips toward $164 bought.
In the bear path, a soft Q4 margin guide, cautious commentary on supply, or a new disclosure from the investigation hits at the same time as the congressional session. A finding that earlier company statements on Megaspeed were inaccurate, a Commerce Department move on Southeast Asian licensing, or any sign that Huang could step aside would push the stock through $164.27 and toward $150. In a worst case where Huang leaves, the market’s informal 30% key-person discount would point well below that, though the order book would cap how far fundamentals justify.
The asymmetry favors patience. The near-term risk is skewed lower because the news flow is controlled by investigators and lawmakers rather than by the company. The medium-term reward is skewed higher because the business is growing at a pace no competitor can match, and the multiple already discounts a lot of bad news. The upside case needs the governance story to stabilize, not to disappear.
NVDA Verdict: Bearish Below $186.64, Upside Target $200
Nvidia is bearish in the near term. The stock fell 4.27% to $178.67 on Monday, then traded at $167.02 by mid-session Tuesday, down 6.52%. It has lost more than 10% in two sessions and sits less than $3 above the $164.27 52-week low and 31% below the $243.37 high. The selling is specific to Nvidia. The board’s independent investigation into Huang’s relationship with a suspected Chinese intelligence asset has no timeline. Bipartisan senators are asking the Commerce Department whether company statements on chip diversion were misleading. House committee chairs want Huang behind closed doors on November 18, the day after earnings. And a newly Democratic Congress, with Warren expected to chair Senate Banking, has every reason to keep the story alive. Macro adds pressure: core CPI at 0.3% for a third month, a 15% chance of a 50bp Fed hike on December 9, and a 2-year yield at 4.736%. A daily close below $164.27 opens $160 and $150. Against that, the fundamentals are the strongest in the sector. Q2 revenue was $96.22 billion, up 106%. Data Center revenue was $89.0 billion, the operating margin 66.2%, and free cash flow $21.3 billion. Q3 is guided to $108.0 billion with no China compute revenue. The company has $99 billion of buyback capacity and trades at 21 times forward earnings. A clean November 17 beat, a firm Q4 guide, a reaffirmed fiscal 2028 growth framework, and clarity that Huang stays would fill the gap to $186.64 and drive the stock to the $200 upside target. A daily close above $186.64 invalidates the bearish view. A break below $164.27 on volume confirms a deeper leg toward $150.