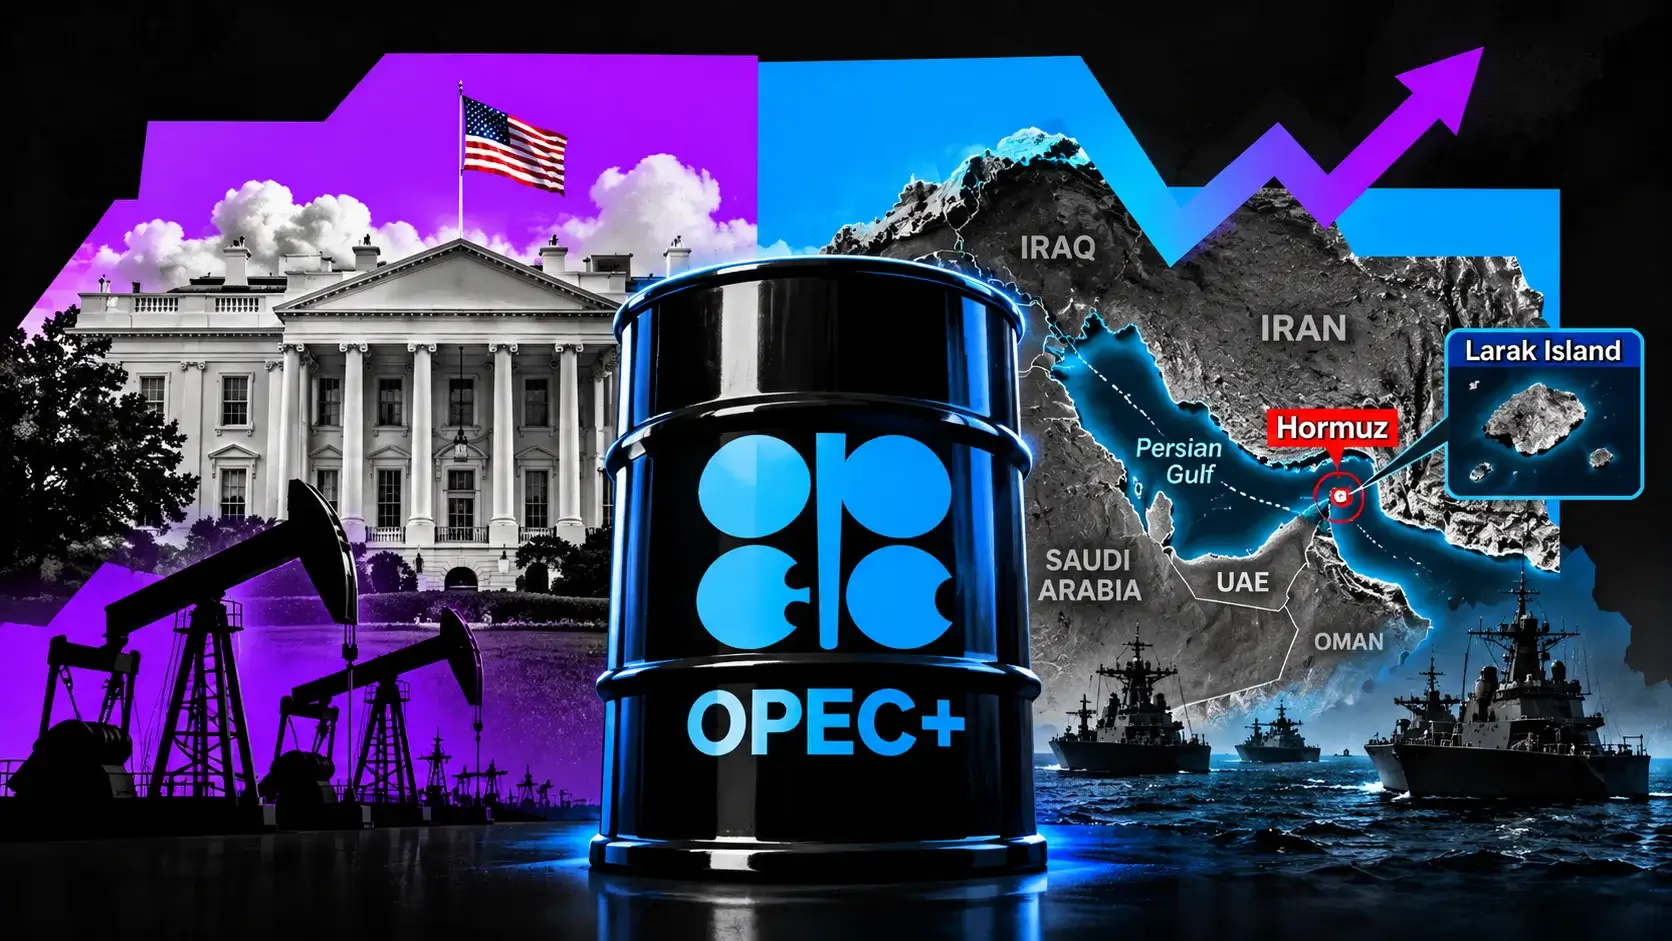
Brent at $103 Trades a $5 Range on Every Iran Headline as Dated Crude Holds $120 and the EIA Sees $85 by December
Saudi flows through Hormuz at 2.9 million barrels per day under U.S. escort and 3.5 million through the Red Sea pipeline have rebuilt exports above 90% of pre-war levels | That's TradingNEWS
Key Points
- WTI $90.94 (−1.79%) and Brent $103.97 after Monday's settle at $92.60 and $105.28; Monday highs $96.54 and $108.83.
- Global inventories down 507 million barrels since February at 2.8 mb/d; 10 mb/d of Gulf output shut in; U.S. SPR at 283 million, lowest since 1983.
- Saudi East-West pipeline restored to 3.5 mb/d; Hormuz flows 2.9 mb/d; sell-side December Brent target $85; escalation zone $115–$120.
West Texas Intermediate for November delivery traded at $90.94 late Tuesday morning, down $1.66 or 1.79%, after settling Monday at $92.60. Brent crude traded at $103.97, down more than 1% from Monday's $105.28 settlement. Monday's session had been the opposite: Brent gained 96 cents to close at $105.28 after spiking to $108.83, and WTI added 19 cents to $92.60 after touching $96.54. Both benchmarks pulled back from those highs in the afternoon as Saudi Arabia restored flows through its East-West pipeline to around 3.5 million barrels per day following repairs. From Monday's high to Tuesday's low, Brent has traded a $4.86 range and WTI a $5.60 range in less than 24 hours on nothing but headlines.
The headlines are the market. On Monday the President rejected Iran's conditional offer to reopen the Strait of Hormuz within seven days, told aides he expects U.S. strikes on Iran to resume after November's midterm elections, and confirmed to reporters that "they made a proposal but I rejected it." Iranian officials cast doubt on reaching any agreement before the midterms, and crude ran to session highs. Then the Saudi pipeline news landed, and the physical supply picture improved enough to knock $3 off Brent before the close. Tuesday brought reports that U.S. and Iranian officials held separate indirect talks with mediators, that Washington's formal response to Tehran's proposal was expected during the day, and that Iran's foreign minister remained in New York after the UN General Assembly waiting for it. Crude gave back another dollar.
Behind the noise, the levels are clear. Brent broke below $100 on September 22 for the first time since September 9, dropping 2.64% to $97.69 on Iran's seven-day offer and the Saudi ramp through Hormuz, its fourth consecutive decline. It reclaimed $100 within days on the rejection and has traded between $100 and $108.83 since. WTI's range over the same window is $88 to $96.54. The market has two prices: a $100 to $105 futures price that reflects a probability-weighted view of a deal, and a Dated Brent physical price that has been holding near $120 because the barrels that actually load in the Gulf still carry a war premium.
The thesis for this forecast: oil at $91 WTI and $104 Brent is priced for a stalemate that neither side can sustain past the midterms. A Hormuz reopening unwinds $10 to $15 of risk premium and takes Brent to $85 to $90 within weeks. An escalation to attacks on shipping takes it to $115 to $120. The base case is a grind between $95 and $108 on Brent through October with the physical market tight, inventories falling 2.8 million barrels a day, and every headline worth $3.
What Actually Moved Monday: The East-West Pipeline at 3.5 Million Barrels and the Yanbu Route
The supply event that capped Monday's rally is the most important physical development of the month. Saudi Arabia has restored flows through its East-West pipeline to around 3.5 million barrels per day following repairs after Houthi attacks forced a temporary halt. The pipeline runs from the Eastern Province oil fields to the Red Sea port of Yanbu, bypassing the Strait of Hormuz entirely, and it has a maximum capacity of 7 million barrels per day. Since Iran began attacking tankers in Hormuz, Yanbu has become the kingdom's key export route, and the pipeline outage earlier in September had forced Saudi Aramco to halt crude loadings at Yanbu and cancel some shipments to European customers.
The outage was expected to cut Saudi crude exports by 400,000 barrels per day for the month. Getting the pipeline back to 3.5 million barrels per day, half its capacity, restores most of that. Combined with the increase in Saudi shipments through Hormuz itself, which averaged about 2.9 million barrels per day over six days through the third week of September with U.S. military assistance, and ship-to-ship transfers in the Gulf of Oman rising to 2.7 million barrels per day from 1.5 million in August, Saudi Arabia is now moving something close to its pre-war export volume through a combination of routes that did not exist in February.
That is the bear case for crude in one paragraph. The kingdom has engineered around the strait. Shuttle vessels carry crude through Hormuz under escort and load it onto tankers waiting outside, and the East-West line carries the rest to the Red Sea. Saudi crude loadings at Gulf ports are up this month. One large trading house scooped up 25 million barrels of discounted Iraqi crude last week. Saudi Arabia sold 100 million barrels to Asia via Hormuz. The barrels are moving.
The bull rebuttal is that the routes are fragile. The East-West pipeline was down for weeks because of Houthi attacks on the Red Sea side, and a Saudi-led coalition intercepted Iran-backed Houthi projectiles as recently as Saturday. The Red Sea route runs through the Bab el-Mandeb strait, a second chokepoint that is also under attack. Hormuz tanker transits have crashed to single digits on some days, with only one commodity vessel leaving the strait on one Wednesday this month. VLCC rates hit a record $1.27 million per day. A shuttle-and-escort system that moves 2.9 million barrels a day through a strait that used to carry 20 million is a workaround, not a solution, and the market knows it. Risk remains skewed toward a larger disruption if the pipeline outage recurs or if Iran, the Houthis or other proxies escalate.
The Negotiation: Seven Days to Reopen, a Rejected Proposal, and Strikes After the Midterms
The diplomatic track is the single largest input to the price and it changed twice in 48 hours. Iran's foreign minister told reporters on the sidelines of the UN General Assembly that "if certain conditions are met, the Strait of Hormuz will be open at the end of seven days, and talks will be restarted." The conditions, conveyed to Washington through mediators, are a lifting of the U.S. blockade of Iranian ports, release of frozen Iranian assets, and a waiver of sanctions on Iranian oil sales. The proposal revives elements of a June plan for ending the standoff and includes resumption of talks aimed at permanently ending hostilities.
The President rejected it. He told aides he expects U.S. strikes on Iran to resume after the November midterms, and he dismissed reports of sanctions relief as a "HOAX" on social media. But the rejection was not the end. U.S. and Iranian officials held separate indirect talks with mediators on Monday, the President confirmed it to reporters without elaborating, and regional officials say the behind-the-scenes effort is continuing. Iran's foreign ministry has said the U.S. must lift its blockade before Tehran will fully open the strait, and Iran and Oman are holding bilateral negotiations over shipping routes.
The history argues for skepticism. The U.S. and Iran signed a memorandum of understanding on June 17 to open Hormuz to commercial ships, and the deal collapsed within days as fighting erupted over which routes vessels could use. Iran launched attacks on tankers transiting along Oman's coast. In August the President told a reporter the U.S. was "only semi-negotiating." In early September the U.S. military destroyed five Iranian crude tankers in retaliation for attempted attacks on a warship, and Iran targeted an aircraft carrier with ballistic missiles. The conflict is in its eighth month, and every prior understanding has proved fragile.
For the price, the negotiation is a binary with a skew. The market has treated Hormuz progress as worth $3 to $5 per barrel per headline, and the September 22 drop below $100 on the seven-day offer is the template for what a genuine deal looks like: a 3% move in a session, another 3% the next day, and a test of $90 Brent within a week. An escalation is worth the same amount in the other direction, and the April 29 spike to $118.03 Brent and $106.88 WTI on a blockade threat is the template for that. The base case, and the one the market is pricing at $104, is neither: a stalemate through the midterms with the physical market doing the work of keeping prices elevated.
The Physical Market: 507 Million Barrels Gone, 10 Million Barrels a Day Shut In, and Dated Brent at $120
The futures price is telling one story and the physical market is telling another, and the physical market is the one that cannot lie. According to the International Energy Agency's September report, global observed oil inventories plunged by 95 million barrels in August, taking cumulative draws since February to 507 million barrels, an average of 2.8 million barrels per day. Global production fell 1.6 million barrels per day month over month to 100.1 million in August as more than 10 million barrels per day of Gulf output remained shut in. Total supply is now forecast to fall 5.7 million barrels per day to 100.7 million for 2026, with the expected Gulf recovery deferred to 2027, when production is projected to rebound by 8 million barrels per day.
The U.S. Energy Information Administration's September outlook tells the same story with different numbers. Global inventories have decreased by roughly 400 million barrels this year, and the agency expects them to continue falling through the end of 2026. Middle East production is forecast to rise gradually as Hormuz flows improve and alternative routes are used, but constraints are expected to persist through year-end, keeping regional output below pre-conflict averages until the second quarter of 2027. The Brent spot price averaged $91 in August, $7 higher than July, and the agency's forecast is $90 for the second half of 2026 before a decline to $77 by the second quarter of 2027 and $74 for 2027 as a whole.
Dated Brent, the physical benchmark, averaged $91 in August and surged to $113.48 on September 9. It has been holding around $120 in recent sessions while futures trade at $100 to $105, a $15 to $20 physical premium that is the largest backwardation in the market's history outside of 2022. That premium exists because the barrels that actually load in the Gulf this month are scarce and the barrels that load in December, when the market expects some form of resolution, are less scarce. A futures trader can wait. A refiner cannot.
The U.S. inventory picture confirms it. Commercial crude stocks are at 424 million barrels, matching the five-year average, but the Strategic Petroleum Reserve has been drawn to 283 to 287 million barrels, its lowest since 1983, after repeated releases. Gasoline inventories are 5.6% below the five-year seasonal average. Distillate inventories are 11.9% below, and the EIA forecasts U.S. distillate stocks will drop below 100 million barrels in September and stay below the five-year low through much of 2027. The American Petroleum Institute reports its weekly inventory data Tuesday evening and the EIA reports Wednesday morning. Both will show draws. The question is only how large.
The Diesel Crisis: $6.50 a Gallon, Distillate Stocks Under 100 Million Barrels, and an Export Ban Debate
The product market is where the war is hitting consumers, and diesel is the epicenter. U.S. retail diesel reached $6.50 per gallon last week, its highest level this year and a record, after crossing $6 for the first time ever in early September. Gasoline hit a Labor Day record of $4.15 per gallon and has stayed above $4 since. The EIA forecasts distillate inventories under 100 million barrels this month and below the five-year low through much of 2027, which is a structural shortage, not a seasonal one. Diesel futures move 3% on the same headlines that move crude 1.5%, because the distillate market has no inventory cushion to absorb a supply shock.
The reason is refining geography. The Gulf states that are shut in or constrained are among the world's largest exporters of middle distillates, and the Red Sea and Hormuz routes that carry Gulf crude also carry Gulf diesel to Europe and Asia. Indian refiners have lifted LPG output nearly 20% as the Hormuz blockage chokes imports, and they are monetizing the crack spread through higher product exports. European diesel is trading at a premium that has sent electric vehicle sales soaring on the continent. U.K. diesel hit a record. The crack spread, the margin between crude and diesel, is at levels that make refiners extraordinarily profitable and consumers extraordinarily squeezed.
The policy risk is a U.S. diesel export ban. The idea has been floated in Washington as a way to cap domestic prices ahead of the midterms, and the analysis from the largest sell-side energy desks is unambiguous: a ban would fill domestic storage, force refineries to cut crude processing, and ultimately raise gasoline prices by reducing overall refinery throughput. It would also remove U.S. barrels from a global distillate market that is already short, pushing European and Asian diesel prices higher and, through the arbitrage, pulling U.S. crude prices down as demand for refinery feedstock falls. A diesel export ban is bearish WTI and bullish global distillates, and it is the single largest policy wildcard between now and November.
For the crude forecast, the diesel crisis matters because it is the transmission mechanism to demand destruction. The chief economist at one of the larger energy consultancies warned last week that "Brent at $100 and diesel at $6.50 a gallon are already squeezing consumers" and that the energy shock could tip into an economic slowdown. The Federal Reserve raised rates on September 16 in part because of energy pass-through into inflation, and the market prices a 70% chance of a second hike in October. High crude produces high diesel produces a Fed hike produces slower growth produces lower crude. That chain is long, but it is the reason the futures curve has December Brent below spot, and it is the reason the EIA's 2027 forecast is $74.
The Macro Overlay: Oil Is Driving the Fed, and the Fed Is Driving Everything Else
Crude is not trading in isolation this week, and the cross-asset picture explains why the futures price is capped near $105 even with the physical market at $120. The 10-year Treasury yield traded at 5.264% Tuesday and the 30-year at 5.589%, both near the highest since 2007. The Federal Reserve raised the funds rate to 3.75% to 4.00% on September 16, the first hike since 2023, citing energy-driven inflation and supply chain disruption from the Middle East conflict. Its projections have PCE inflation at 3.7% for 2026 and the policy rate at 4.1% through 2027. Monday's oil spike to $108.83 Brent pushed the 10-year to a 5.27% intraday high and pushed October hike odds from 49% to roughly 70%.
That is the feedback loop. Higher oil means higher inflation means the Fed hikes means yields rise means the dollar firms means oil, priced in dollars, faces a headwind, and means growth slows, which cuts demand. Monday's equity session showed it: the Dow fell 347 points, the S&P 500 lost 0.77%, the Nasdaq dropped 0.92%, and the Energy Select Sector SPDR XLE fell 0.9% despite Brent near $105 because the market is pricing the end of the oil spike, not its continuation. Airlines got hit on jet fuel math and cruise lines rallied Tuesday when crude fell. The equity market is trading oil as a tax, not as a commodity.
The dollar was flat Tuesday, which removes one headwind. But the broader point stands: at $105 Brent the market is already pricing enough demand destruction and enough Fed tightening that the upside from here requires a genuine supply shock, not just a failed negotiation. The largest sell-side energy desks have Brent at $85 and WTI at $80 for December 2026, with $80 and $75 for 2027, and their $120-plus scenario requires Gulf output to remain 4 million barrels per day below pre-war levels through 2027 with intensified shipping attacks in Hormuz and the Red Sea. That is the tail, not the base.
Speculative positioning is the other constraint. Managed money is already extremely long crude, and one large bank warned that further gains require a fresh physical supply shock because the financial buyers are fully deployed. A market that is already long, facing a Fed that is hiking on its account, with the physical premium at $15 to $20 over futures, is a market where the futures price rises only if the physical shortage gets worse. That is why $108.83 was sold Monday and why $100 has held as support: the range is defined by a physical floor and a macro ceiling.
Technicals: $100 Brent Is Support, $108.83 Is Resistance, and $118 Is the April High
The chart on Brent is a range within a larger uptrend. Support first. $103.97 is Tuesday's print and roughly the midpoint of the September range. $101.21 is the September 9 close, the highest since May 22 at the time and now a pivot. $100 is the round number, the level that has been tested and held on a closing basis since September 22, and the line between a stalemate market and a deal market. $97.69 is the September 22 low on the seven-day offer and the level a genuine deal takes out. $97.92 and $99.05 are the early-September closes. $94.29 is the late-summer settle and the top of the pre-September range. $91 is the August average and the EIA's second-half forecast. $87.72 is the August 10 close on the last round of Hormuz optimism and the level that marks a full unwind of the September premium. $85 is the December 2026 sell-side target and the bear case destination.
Resistance next. $105.28 is Monday's settlement. $106 is where Brent traded early Tuesday before the reversal. $108 is the round number and the area of Monday's spike. $108.83 is Monday's high and the September high. $113.48 is the Dated Brent spike on September 9 and a level the futures market has not tested. $115 to $120 is the escalation zone that the more constructive desks say requires serious attacks on shipping in the strait. $118.03 is the April 29 close, the 2026 high, set on the blockade threat. $120 is where Dated Brent has been holding and the ceiling for any futures rally short of a full closure.
On WTI the ladder is compressed. $90.94 is Tuesday's print. $90 is the round number and near-term support. $88.68 is the late-summer settle. $85 is the level that opens $82.13, the August 10 close. $80 is the December sell-side target. Above, $92.60 is Monday's settle, $94.04 is the early-September high, $96.05 is the September 9 close, $96.54 is Monday's high, $97.87 is the spring spike, and $106.88 is the April 29 high. WTI has traded above Brent at points this year, with the spread the widest since 2009, and the November contract's discount to Brent at $13 is the market's view that U.S. barrels are more available than Gulf barrels.
The pattern is a range between $100 and $108.83 on Brent that has held for two weeks with the physical market at $120 overhead and the macro at $85 below. A daily close below $100 on a confirmed deal targets $97.69, then $94, then $91 within two weeks. A daily close above $108.83 on an escalation targets $113.48 and $118. Inside the range, every headline is worth $3 and the trade is to fade the extremes.
Read More
-
Yen Stalls at 160 Despite a 3% JGB and Tokyo Core CPI at 2.0% — Intervention Sits at 164, Friday's Payrolls Decide
02.09.2026 · TradingNEWS ArchiveEnergy
-
Iovance IOVA Rips to $13.64 on a $55M Guidance Raise as Amtagvi Runs 40% Quarter Over Quarter
29.09.2026 · TradingNEWS ArchiveStocks
-
Ethereum at $2,714 Fights $2,800 With a Golden Cross Behind It and a 5.26% 10-Year in Front of It
29.09.2026 · TradingNEWS ArchiveCrypto
-
Gold at $4,193 Fights to Hold the $4,139 Double Bottom as Newmont NEM Drops 4% and Gold Fields GFI Craters 12.9%
29.09.2026 · TradingNEWS ArchiveCommodities
-
Dow Slips to 51,385, S&P 500 Flat at 7,681, Nasdaq 26,826 as Fair Isaac FICO Craters 21.6% and Carnival CCL Surges 11.8%
29.09.2026 · TradingNEWS ArchiveMarkets
-
GBPUSD at 1.3230 Sits on a 1.3200 Double Floor With a 12.5-Basis-Point Fed–BoE Spread and a 10-Year Gilt at 5.22%
29.09.2026 · TradingNEWS ArchiveForex
Supply Beyond the Gulf: The Americas Quintet, Russia's Vostok, and OPEC+ Spare That Cannot Reach the Market
The supply response outside the Gulf is real and it is not enough. The IEA's "Americas Quintet" of the United States, Canada, Brazil, Guyana and Argentina dominates non-OPEC+ growth, adding 1.4 million barrels per day in 2026 and another 1 million in 2027. Russia began oil exports from its giant Vostok Arctic project this month. The U.S. is backing Argentina's first LNG export project with a $6 billion loan. U.S. commercial crude stocks are at the five-year average even after the SPR draw to 283 million barrels, which means domestic production is holding up under $90 WTI. None of that offsets 10 million barrels per day of shut-in Gulf output.
OPEC+ is the constraint that does not bind. The group's spare capacity sits almost entirely in the Gulf states that cannot export it, and the cartel's planned reversal of voluntary cuts, which was the bearish overhang before the conflict began, is irrelevant when the barrels cannot leave the region. Saudi Arabia is producing what it can move, which is 3.5 million barrels per day through the pipeline plus 2.9 million through Hormuz under escort, against a pre-war export volume above 7 million. Iraq is selling discounted crude to whoever will take it. Iran's own output is shut in by the blockade and excluded from the IEA's OPEC+ tally. Kuwait and the UAE are constrained by the same strait.
The spare capacity story therefore inverts. In a normal market, OPEC+ spare capacity caps prices because the cartel can release barrels. In this market, the spare capacity is physically trapped, which means it cannot cap prices, but it also means that the moment the strait reopens, 10 million barrels per day of shut-in production plus the trapped spare capacity comes back within weeks, not months. The IEA's 8 million barrel per day rebound forecast for 2027 is the base case. A faster reopening pulls that forward into the fourth quarter, and that is the scenario in which Brent does not stop at $90 but goes to $80.
The demand side is softer than the headlines suggest. Global demand growth has slowed under $100 crude, the Chinese economy is absorbing record fuel costs, European EV sales are soaring on diesel prices, and the Fed is tightening into an energy shock. The IEA's supply number of 100.7 million barrels per day for 2026 is down 5.7 million from 2025, but demand is also down from pre-war forecasts by more than 1 million, which is why inventories are falling at 2.8 million barrels per day rather than 4 million. The market is rationing by price, and the price at which it rations is $100 Brent.
The Equity Read: Energy Stocks Sold on a $105 Print, and What That Says About the Top
The Energy Select Sector SPDR XLE fell 0.9% on Monday with Brent at $105 and the S&P 500 down 0.77%. On a day when crude touched $108.83 intraday, the largest energy ETF underperformed the broad market. That is not what a market expecting higher oil looks like. It is what a market expecting the oil spike to end looks like, and it is consistent with every other piece of positioning data: speculators are already long crude, the futures curve is backwardated with December below spot, and the sell-side has December Brent at $85.
The producer stocks tell the same story. Exxon and Chevron have lagged the crude price through September because the equity market is discounting a mean reversion that the futures market has not fully priced. The refiners are the winners, with the diesel crack spread at record levels and U.S. refiners exporting distillates at margins that have not existed since 2022. The tanker companies are printing money at $1.27 million per day VLCC rates. The airlines and cruise lines are the losers on jet fuel, which is why Carnival's 11.8% rally Tuesday on a record quarter came with crude down 1.79%.
The read-through for the crude forecast is that the equity market has already made its call. It has priced energy stocks for $85 to $90 Brent by year-end, it has priced refiners for a diesel crack that stays wide, and it has priced airlines for fuel costs that stay high through the fourth quarter but not into 2027. That is a market betting on a resolution between now and the midterms, not on an escalation. The equity market is not always right about commodities, but it is usually right about direction over a three-month horizon, and its direction is down.
The contrary read is that energy stocks are cheap on any crude price above $80, that the sector's underperformance reflects the same rate shock hitting every capital-intensive business rather than a specific view on oil, and that a $120 escalation would produce a 20% rally in XLE from levels that already discount $85. That is the bull case for the sector, and it is a hedge against the scenario in which the negotiation fails. But it is a hedge, not a base case, and the base case in the equity market is that the September spike was the high.
Bull Case: Talks Collapse, Shipping Attacks Resume, Brent Retests $118
The bull case for crude is the negotiation failing loudly. The President has rejected Iran's proposal and told aides he expects strikes to resume after the midterms. Iranian officials doubt a deal before November. The June memorandum collapsed within days. The U.S. destroyed five Iranian tankers three weeks ago and Iran targeted an aircraft carrier. The Houthis attacked Saudi energy facilities and the East-West pipeline this month and were intercepted again Saturday. Hormuz transits are in single digits on bad days. VLCC rates are at a record. The physical market is at $120. Every element of a supply shock is in place except the trigger.
The trigger is an attack on shipping that takes the shuttle-and-escort system offline. Saudi flows through Hormuz at 2.9 million barrels per day depend on U.S. naval escort and on Iran choosing not to fire at escorted vessels. Two tankers were attacked in the strait the same week Iran floated the seven-day offer. If Iran or its proxies hit an escorted tanker, or hit the East-West pipeline again, the 3.5-million-barrel Saudi workaround fails and the market loses 5 to 6 million barrels per day of the supply it has been counting on. That is the scenario in which the largest sell-side desk sees Brent above $120 in 2027, and it is the scenario in which the April 29 high at $118.03 gets retested in October rather than 2027.
The path is a daily close above $108.83, which takes out the September high and confirms the range has broken up. From there $113.48, the Dated Brent spike, is the first target, and $118.03 is the second. WTI follows to $96.54, then $100, then $106.88. The move from $103.97 to $118 is 13.5%, and it would come in days, not weeks, because the speculative positioning that is already long would be joined by physical buyers who have been waiting for the futures price to reflect the Dated premium.
The macro consequence is severe. Brent at $118 is diesel at $7.50, a Fed that hikes in October and December, a 10-year at 5.50%, and an equity market that loses 10%. That is why the bull case for crude is not the bull case for anything else, and why the President's incentive to reach a deal before the midterms is as strong as Iran's. The bull case is a 25% probability, and it is the tail that the $15 physical premium is insuring against.
Bear Case: Hormuz Reopens, 10 Million Barrels Return, Brent to $85 by December
The bear case for crude is the negotiation succeeding, and the pieces are in place for that too. Iran has offered to reopen the strait within seven days. Back-channel talks continued Monday even after the public rejection. Gulf oil flows have reverted to more than 90% of pre-war levels by some tanker-tracking estimates, which means Iran is losing leverage as the strait becomes less of a chokepoint and more of a nuisance. The Iranian economy is under severe strain from the blockade and the sanctions. The U.S. midterms are five weeks away and the President has a $6.50 diesel problem. Both sides have reasons to deal, and the June memorandum, however briefly it held, proves a framework exists.
The trigger is a confirmed reopening with verified tanker transits. The September 22 session is the template: Brent fell 2.64% to $97.69 and WTI fell 4.5% on the seven-day offer alone, before any barrels moved. A deal that actually moves barrels takes Brent through $97.69 in a session, through $94.29 in two, and to the $91 August average within a week. From there the EIA's $90 second-half forecast becomes a ceiling rather than a target, and the $85 December sell-side number is the destination. WTI follows to $85, $82.13 and $80. The move from $103.97 to $85 is 18.2%, and it unwinds the entire September premium plus part of the summer's.
The physical market would lag but follow. Dated Brent at $120 reflects barrels loading this month; a reopening takes the October and November loading premium out first, and the $15 to $20 backwardation collapses toward $5 within a month. The 10 million barrels per day of shut-in Gulf output restarts in phases over eight to twelve weeks, the IEA's 2027 rebound pulls forward into the fourth quarter, and global inventories stop falling at 2.8 million barrels per day and start rebuilding. The EIA's 2027 average of $74 becomes the second-quarter 2027 number rather than the full-year number.
The macro consequence is the mirror of the bull case: diesel back under $5, October hike odds back under 40%, the 10-year back toward 5.0%, and an equity market that rallies on the removal of the largest single inflation input. The bear case for crude is the bull case for everything else, and it is the outcome that every other market is already leaning toward. It is a 40% probability on current headlines, and it rises with every day the back-channel talks continue without a breakdown.
What to Watch: Washington's Response, API Tonight, EIA Tomorrow, and the Midterm Clock
The immediate catalyst is Washington's formal response to Iran's proposal, which was expected Tuesday. Any language that keeps the door open, even while rejecting the specific terms, is worth $2 to $3 down on Brent. Any language that closes it is worth the same up. The President's comment that strikes resume after the midterms sets a five-week window in which the market will price a deal as a possibility, and a strike as a certainty after November 3 if no deal is reached. That asymmetry is why the curve is backwardated into December and why the physical premium is so large: the market is paying up for barrels that load before the strikes resume.
The data calendar is dense. The American Petroleum Institute reports weekly inventories Tuesday evening. The EIA reports Wednesday morning, and the numbers to watch are distillate stocks against the sub-100-million-barrel forecast, the SPR level against 283 million, and Cushing crude stocks, which set the WTI curve. The IEA's October report lands mid-month and will update the 10 million barrel per day shut-in figure. OPEC+ meets on its usual schedule but has nothing to decide while its barrels are trapped. The Fed's October 28 meeting is the macro event, and oil is the single largest input to it.
The tanker data is the daily tell. Saudi flows through Hormuz above 3 million barrels per day and East-West pipeline flows above 3.5 million confirm the workaround is holding. Hormuz transits falling back to single digits, or a halt in Yanbu loadings, confirm it is not. The VLCC rate at $1.27 million per day is the price of the workaround; a decline in that rate means the strait is opening, and a further spike means it is closing. Ship-to-ship transfers in the Gulf of Oman at 2.7 million barrels per day are the volume the escort system can handle; a number above 3.5 million means Saudi Arabia has found more capacity.
The wildcards are a U.S. diesel export ban, which is bearish WTI and bullish global distillates and would be announced with no warning; a Houthi strike on the East-West pipeline or Yanbu, which takes 3.5 million barrels off the market for weeks; and a Hormuz shipping attack, which is the bull-case trigger. Each is a $5 to $10 move in a session. The market has priced none of them at $104 Brent, and it has priced all of them at $120 Dated.
Verdict: Neutral in the $100–$108 Range, Sell a Close Above $108.83, Buy a Confirmed Deal Below $97
Crude at $90.94 WTI and $103.97 Brent is a range trade with a bearish skew over three months and a bullish skew over three days. The physical market at $120 Dated Brent, inventories falling 2.8 million barrels per day, 10 million barrels per day shut in, distillate stocks under 100 million barrels, diesel at $6.50, and a President who has rejected Iran's offer and promised strikes after the midterms are the reasons the futures price cannot fall below $100 without a deal. The Saudi East-West pipeline at 3.5 million barrels per day, Hormuz flows at 2.9 million under escort, Gulf exports above 90% of pre-war by some counts, back-channel talks that continued through the public rejection, a Fed hiking on oil's account, speculators already fully long, and a sell-side that has December Brent at $85 are the reasons the futures price cannot rise above $109 without an escalation.
The forecast: Brent trades $100 to $108 through the first week of October with the direction of the eventual break decided by the negotiation, not the data. A confirmed reopening takes it to $97.69, $94 and $91 within two weeks and $85 by December, an 18% decline, and WTI to $85, $82 and $80. A confirmed escalation, meaning an attack on escorted shipping or the Saudi pipeline, takes it to $113.48 and $118 within days, a 13.5% gain, and WTI to $100 and $106.88. The odds are 40% deal, 25% escalation, 35% stalemate, and the stalemate outcome produces a slow grind lower as the workarounds improve and the macro tightens.
The trade is to fade the range. Sell Brent on any close above $108.83 with a stop at $113.48 and a target at $100, because the equity market, the futures curve, the sell-side and the Fed are all leaning against the spike. Buy Brent on a confirmed deal below $97.69 with a stop at $94 and a target at $100, because the first move on a deal overshoots and the physical market takes weeks to normalize. Inside the range, WTI at $90.94 is fair value for a stalemate, and the November contract's $13 discount to Brent is the market's way of saying U.S. barrels are the safest supply on earth right now.
The long-term view is unchanged by the week's noise. The EIA has 2027 at $74, the sell-side has it at $80, and the IEA has 8 million barrels per day of supply coming back. Every one of those numbers assumes the strait reopens by mid-2027, and every one of them is $20 to $30 below where Brent trades today. Oil at $104 is a price that only survives if the war continues, and the war is the one thing neither side can afford to continue past November.