Brent ($101.61) Reclaims $100 as Libya Supply Shock Beats Iran Talks — WTI Range Set at $88 to $95
WTI swung $2.28 from its $89.64 low as El Sharara went offline | That's TradingNEWS
Key Points
- WTI climbed 1.55% to $91.92 as Libya's El Sharara field, a third of national output, went offline.
- The EIA reported a 2.969 million-barrel crude build against a 600,000-barrel expected draw.
- Global oil inventories are falling 3.0 million barrels a day in Q3 as the SPR sits at 285 million barrels.
Oil broke a five-session losing streak on Wednesday, and it did it on a supply shock rather than a demand signal. November WTI traded at $91.92 by mid-morning, up $1.40 or 1.55%, after starting the day as low as $89.64. Brent climbed to $101.61, up 2.37%, pushing back above the $100 line it had lost earlier in the week. The swing from the WTI low to the mid-morning high measured $2.28, a 2.5% intraday reversal.
The trigger came from North Africa. An armed group shut a valve on the pipeline from Libya's El Sharara field, which accounts for roughly a third of the country's output, abruptly taking significant supply offline. That outage landed in a market where global inventories have already fallen by 400 million barrels this year and where any lost barrel competes for a thin cushion.
The early-morning move pointed the other way. WTI fell 0.97% to $89.64 and Brent slipped 0.24% to $99.01 in early trading after President Trump described three hours of talks with Iranian representatives at the United Nations as very productive, with another meeting scheduled. Diplomacy pushed prices lower overnight. Libya pushed them back up during the European session.
The U.S. inventory data then tempered the bounce. The EIA reported a commercial crude build of 2.969 million barrels for the week to September 18, against expectations for a 600,000-barrel draw, with stocks at the Cushing hub up 2.266 million barrels. Crude futures slipped in a delayed reaction. A near 3.6 million-barrel miss against consensus is a bearish surprise that caps how far the Libya rally can run.
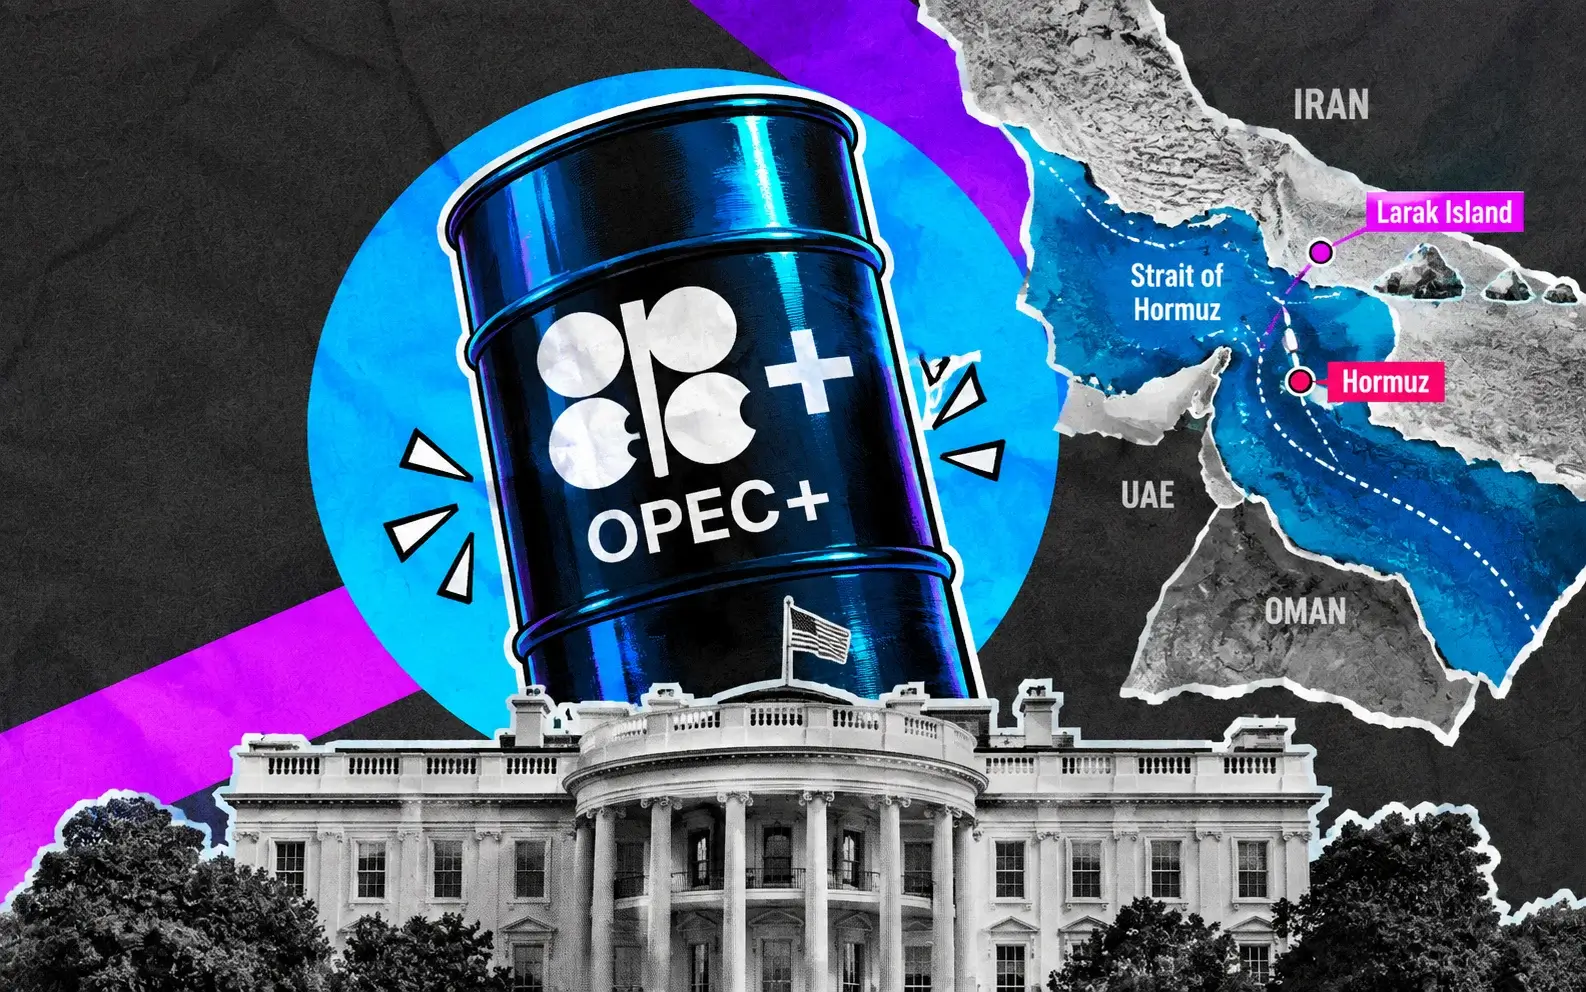
That sets up the forecast. The market is pulled between two forces. The first is structural tightness: a Middle East war that has cut Gulf exports, global inventories that are still falling at 3.0 million barrels a day this quarter, a Strategic Petroleum Reserve down to 285 million barrels and diesel stocks at a severe deficit. The second is diplomatic and physical relief: U.S.-Iran talks, Hormuz flows at a six-month high and Saudi Arabia preparing to restart its East-West pipeline to bypass the strait.
The thesis is direct. As long as the war keeps Gulf output below pre-conflict levels and global stocks keep drawing, Brent holds a floor near $95 and WTI near $88. The upside is capped by diplomacy, a strong dollar and a Fed hiking into an oil-driven inflation surge. Brent should trade between $95 and $105 into October, with WTI between $87 and $95, and a breakout in either direction depends on Iran.
Session Tape: From $89.64 to $91.92, Then an EIA Surprise
The day unfolded in three distinct legs. The overnight session carried the diplomatic optimism from Tuesday. By early trading, WTI had fallen 0.97% to $89.64 and Brent had slipped 0.24% to $99.01. U.S. stock futures were flat and got a small boost as oil extended recent declines, with Brent below $100 despite continued tough talk from both Washington and Tehran.
The second leg came from Libya. News that an armed group had shut the El Sharara pipeline valve turned crude higher through the European morning. The market had spent five sessions pricing de-escalation, and a sudden supply outage exposed how little spare cushion remains. Brent rose above $101 after the five straight losing sessions, as traders weighed efforts to restore flows disrupted by the Middle East conflict.
The third leg came with the U.S. data. At 9:45 a.m. ET, the September flash PMI showed U.S. business activity at its strongest in more than five years, with input costs rising at the fastest rate since October 2022, driven by fuel and transport costs. By 10:34 a.m. ET, November WTI traded at $91.92, up 1.55%. At 10:30 a.m. ET the EIA weekly report hit, showing a 2.969 million-barrel crude build against an expected 600,000-barrel draw, and crude futures slipped in a delayed reaction.
The structure of the session matters for positioning. The Libya outage is a genuine supply loss, but the U.S. data shows domestic crude stocks rising, which limits how much of that outage the market can price into WTI. Brent, the global benchmark, reflects the Libya and Middle East risk more directly. WTI reflects U.S. balances, where crude is comfortable and products are tight.
The WTI-Brent spread shows that split. With WTI near $91.92 and Brent near $101.61, the spread sits near $9.70 a barrel. A spread that wide signals a global market tighter than the U.S. market, which makes sense when Middle East exports are constrained while U.S. commercial crude sits near its five-year average. A wide spread also supports U.S. crude exports, which will keep pulling barrels out of the country.
The levels for the rest of the session are clear. For WTI, $90.52, Tuesday's close, is the first support, and $89.64, Wednesday's low, is the second. A close above $92 would keep the reversal intact. For Brent, holding above $100 is the line that separates a supply-driven bounce from a failed rally.
Libya's El Sharara Outage: A Third of Output Offline
The single largest driver of Wednesday's move is the Libya disruption. An armed group shut a valve on the pipeline carrying crude from El Sharara, Libya's largest oil field, which accounts for roughly a third of the country's output. The blockade suddenly took significant supply offline and kept traders on edge.
Libya's supply has a long history of interruption. Political fragmentation between rival governments, armed groups controlling infrastructure and disputes over revenue sharing have repeatedly shut fields and export terminals. Outages can last days or months. The market cannot price a duration, only a risk, and that uncertainty itself adds a premium.
The timing makes the outage more damaging than usual. In a normal market, the loss of a third of Libya's output could be absorbed by spare capacity elsewhere in OPEC. In 2026, spare capacity is constrained by the Middle East war. Global oil inventories fell by an estimated 3.9 million barrels a day in the second quarter of 2026, and the draw is expected to continue at 3.0 million barrels a day in the third quarter and 1.7 million barrels a day in the fourth. A market already drawing 3 million barrels a day has no room to lose another supplier without price rising.
The quality of the crude adds to the impact. Libyan crude is light and sweet, prized by European refiners for gasoline and diesel yields. With diesel already at record prices in the U.S. and distillate stocks tight, losing a high-quality light crude supply puts direct pressure on the product market. European refiners will bid harder for replacement barrels, which supports Brent more than WTI.
The outage also interacts with diplomacy. On the same day Libya went offline, the U.S. and Iran were pursuing talks that could restore Gulf flows. The market is now weighing a certain near-term supply loss in Libya against an uncertain future supply gain from Iran. Certain losses tend to move prices more than uncertain gains, which is why Libya won Wednesday's session.
For the forecast, the duration of the El Sharara shutdown is a key variable. A resolution within days would remove much of Wednesday's premium and send Brent back toward $99. A shutdown that stretches into October, especially if it spreads to other fields or export terminals, would push Brent toward $105 and keep WTI above $92. Libyan outages have a track record of lasting longer than first expected.
EIA Weekly Report: A 2.97 Million-Barrel Crude Build and Cushing Refills
The official U.S. data delivered a bearish surprise. The EIA reported a commercial crude inventory increase of 2.969 million barrels for the week ending September 18, against expectations for a 600,000-barrel draw and following a 640,000-barrel draw the prior week. Crude stocks at Cushing, Oklahoma, the delivery point for WTI futures, rose 2.266 million barrels after a 342,000-barrel draw the week before. Crude futures slipped after the release.
The miss matters because it breaks a trend. The prior week's report had shown commercial crude stocks falling 640,000 barrels to 423.4 million barrels, a third consecutive weekly draw. Adding 2.969 million barrels lifts commercial stocks to roughly 426.4 million. Commercial crude had been about 1% above its five-year seasonal average, the one part of the U.S. balance sheet not showing shortage. A build of nearly 3 million barrels pushes that surplus wider.
Cushing is the more important number for WTI. Cushing had fallen to 21.5 million barrels in the prior week, a thin working inventory at the WTI pricing point after earlier summer prints near operational lows. A 2.266 million-barrel build lifts Cushing to roughly 23.8 million barrels, an 11% jump in a single week. Rising stocks at the delivery hub ease the tightness that had been supporting the front of the WTI futures curve.
The API had flagged the direction. The industry's Tuesday estimate showed a 1.8 million-barrel increase in crude stockpiles, with gasoline and distillate inventories declining. The API showed crude building against an expected draw while products drew down against flat consensus, a mixed signal going into the official release. The EIA confirmed the crude build and made it larger.
Distillates stayed tight. The EIA reported distillate stocks fell 428,000 barrels, against an expected draw of 600,000 barrels, after a 1.585 million-barrel build the prior week. Distillate fuel production fell 68,000 barrels a day after a 121,000 barrel-a-day decline the week before. Lower diesel production with stocks still drawing keeps the middle-distillate market as the tightest part of the U.S. complex.
The full data is on the EIA Weekly Petroleum Status Report page, which introduced a new summary format with this week's release.
For the forecast, the report is bearish for WTI in the near term and neutral for Brent. A crude build with Cushing refilling caps WTI's upside near $92 to $93. Tight distillates keep refining margins and diesel prices elevated. The key follow-through is whether the crude build repeats next week, which would signal that higher prices are curbing U.S. demand.
Diesel Is the Binding Constraint: Record Prices and an Export Ban on the Table
The U.S. oil market's real shortage is in diesel, not crude. Commercial crude is not in crisis; diesel is. Until distillate stocks rebuild toward normal and retail diesel comes off its record, consumers keep paying more for transport, and middle-distillate tightness is the binding constraint on the market rather than the weekly crude print. Wednesday's 428,000-barrel distillate draw keeps that constraint in place.
Policy is now in play. Treasury Secretary Scott Bessent said the administration is examining whether a diesel export ban is a feasible way to address record-high prices for the fuel. President Trump has floated a ban on U.S. diesel exports. A ban would keep more diesel inside the U.S., lowering domestic prices, but it would pull supply away from Europe and Latin America, which rely on U.S. diesel.
The market impact of a ban would be complex. A diesel export ban would be short-term positive for prices but carry worse long-term consequences. In the short run, removing U.S. diesel from global markets would lift international diesel prices and refining margins outside the U.S. That would support Brent-linked crude demand from foreign refiners seeking to replace the lost U.S. supply. Over time, a ban would distort trade flows, discourage U.S. refinery investment and risk retaliation.
The inflation link is direct. High diesel prices act as an inflationary pressure on everything that moves by truck. That feeds directly into the PMI's finding that fuel and transport were the top reasons for input costs rising at their fastest pace since October 2022. Diesel prices are therefore not just an energy market story; they are a Fed story. Every week that diesel stays at a record adds to the case for another rate hike.
Refining capacity limits the fix. Distillate fuel production fell for a second consecutive week, down 68,000 barrels a day after a 121,000 barrel-a-day decline. Refiners cannot quickly produce more diesel when the crude slate is constrained and maintenance season approaches. The loss of Libya's light sweet crude, which yields high diesel volumes, makes the problem worse.
For the forecast, diesel supports the crude floor even when crude stocks build. Refiners facing record diesel margins will keep running hard, which keeps demand for crude elevated. An export ban would be a bullish shock for global diesel and Brent. The absence of a ban, combined with a slow rebuild in distillate stocks, keeps crack spreads wide and supports crude prices near current levels.
The Iran Track: Talks at the UN and Hormuz Flows at a Six-Month High
Diplomacy is the biggest downside risk for crude. On Tuesday, the U.S. and Iran held three hours of talks at the United Nations through Qatari mediation, and President Trump described the meeting as very productive, saying another session is scheduled soon. That news pushed WTI and Brent lower overnight and was the main reason Brent fell below $100 earlier in the week.
The optimism has limits. Iran denied it had dropped its preconditions for reopening the Strait of Hormuz. A foreign ministry spokesperson confirmed the talks took place but described them as a channel for conveying Iran's terms, including an end to the war in all its dimensions, the end of the naval siege and the economic war, and the release of Iranian assets. Those conditions are far from anything Washington has signalled it would accept.
The rhetoric remains harsh. In his UN address, President Trump said he faced a choice between making a deal to end the war or annihilating the Islamic Republic. He has also indicated that a deal is more likely after the midterm elections, which are six weeks away. That timeline means the geopolitical premium in crude will not fully disappear before November.
Physical flows are improving regardless. The head of U.S. Central Command said oil and LNG shipments through the Strait of Hormuz over the past two weeks reached their highest level in six months. Qatar's prime minister urged Gulf states to cooperate on restoring regional stability and said messages were being exchanged between the U.S. and Iran. More ships moving through the strait means more supply reaching markets, which has been the main driver of the five-day decline before Wednesday.
Saudi Arabia is adding an alternative route. The kingdom is preparing to restart exports through its East-West pipeline in the coming days, which would let it bypass the contested Strait of Hormuz and increase outbound shipments. A functioning East-West pipeline would add capacity that does not depend on Iran's cooperation, a structural bearish factor for Brent.
For the forecast, Iran determines the direction of the next big move. A framework deal that reopens Hormuz fully would likely push Brent toward $90 and WTI toward $85, as the market prices a return of shut-in Gulf production. A breakdown in talks or a military escalation would push Brent back above $105. The base case, with talks continuing but no deal before November, keeps Brent oscillating around $100.
Read More
-
Yen Stalls at 160 Despite a 3% JGB and Tokyo Core CPI at 2.0% — Intervention Sits at 164, Friday's Payrolls Decide
02.09.2026 · TradingNEWS ArchiveEnergy
-
IONQ Holds 5% Gain as Nasdaq Drops 1% — Decoder Breakthrough Sets Up $50 Test
23.09.2026 · TradingNEWS ArchiveStocks
-
XRP-USD ($1.56) Tests $1.50 After Rate Shock — Break of $1.70 Opens 28% Upside to $2.00
23.09.2026 · TradingNEWS ArchiveCrypto
-
Gold ($4,318) Breaks Lower on Rate Shock — Central Bank Floor Near $4,000 Caps 7.4% Downside
23.09.2026 · TradingNEWS ArchiveCommodities
-
Nasdaq Drops 290 Points, S&P 500 Loses 0.54%, Dow Holds 51,772 as META Rallies 2.9%
23.09.2026 · TradingNEWS ArchiveMarkets
-
GBPUSD (1.3272) Breaks July Range on Rate-Gap Flip — £18.3B Borrowing Miss Targets 1.3100
23.09.2026 · TradingNEWS ArchiveForex
The EIA Outlook: $90 Brent, 400 Million Barrels Drawn and a 2027 Decline
The official forecast frames the medium-term picture. In its September Short-Term Energy Outlook, the EIA said global oil prices rose to an average of $91 a barrel in August, $7 higher than in July, as global inventories fell by an estimated 400 million barrels so far this year. The agency expects inventories to keep falling through the end of 2026, keeping prices near the August average in the coming months.
The forecast was raised. The EIA now expects Brent to average around $90 a barrel in the second half of 2026, $8 higher than in its previous outlook. That upgrade reflects the persistence of Middle East disruptions and the size of the inventory drawdown.
The draw rates are severe. The EIA estimates global oil inventories fell by an average of 3.9 million barrels a day in the second quarter of 2026 and will fall by another 3.0 million barrels a day in the third quarter and 1.7 million barrels a day in the fourth. A 3 million barrel-a-day draw means the world is consuming far more oil than it produces, with inventories filling the gap. That cannot continue indefinitely, which is why prices must stay high enough to restrain demand.
The recovery path is gradual. The EIA forecasts Middle East oil production will rise in the coming months through increasing Hormuz flows and alternative routes, but it assumes some export constraints persist through year-end, keeping regional production below pre-conflict levels until the second quarter of 2027. As exports rise and shut-in production restarts, the agency expects prices to fall to an average of $77 by the second quarter of 2027, then to $67 in the second half of 2027 as inventories rebuild.
The gap between the forecast and the market is small. Brent at $101.61 on Wednesday sits roughly $11 above the EIA's $90 second-half average. That premium reflects the Libya outage, diesel tightness and war risk. For the EIA forecast to hold, Brent would need to average below $90 over the rest of the year, which requires a sustained decline from current levels.
The long-term curve points lower. A forecast path from $90 in late 2026 to $67 by late 2027 implies a 25% decline over 12 to 15 months. That shape reflects a market that expects supply to recover once the war eases. The futures curve likely shows backwardation, with near-month prices above later months, consistent with a tight present and a looser future.
For the forecast, the EIA outlook supports a $95 to $105 Brent range near term with a bearish tilt into 2027. The biggest risk to the lower path is a war that lasts longer than the EIA assumes.
Strategic Reserves at 285 Million Barrels: The Missing Buffer
The U.S. government has less ability to cushion price spikes than at any point in decades. The Strategic Petroleum Reserve dropped another 403,000 barrels to 285 million barrels in the latest reporting week. A year ago, the reserve stood above 400 million barrels. That is a decline of more than 115 million barrels, roughly 29%, in twelve months.
The historical context is striking. Earlier this summer, the SPR hit its lowest level since April 1983, while total U.S. crude including the SPR sat near 726.2 million barrels, close to the October 1984 low. The SPR was built to protect the U.S. economy from exactly this kind of supply disruption. After a year of releases, the buffer that used to sit in the reserve is no longer there.
The implications for pricing are direct. When the SPR is full, the market knows the government can release barrels to cap price spikes, which limits the upside risk premium in futures. With the reserve depleted, that backstop weakens. A new supply shock, like Wednesday's Libya outage, hits prices harder because traders cannot count on the same scale of emergency release.
The political pressure adds uncertainty. With diesel at record prices and midterm elections six weeks away, the administration has limited tools. SPR releases would drain a reserve already near multi-decade lows. A diesel export ban is under review. Pressuring OPEC producers or pursuing an Iran deal are the remaining levers. Each carries costs and uncertain timing.
Commercial stocks partly offset the weakness. U.S. commercial crude inventories sit near 426 million barrels after Wednesday's build, about 1% above the five-year average before the latest increase. The problem is not crude in commercial tanks; it is the combination of low strategic reserves, tight diesel and a global market drawing 3 million barrels a day.
The refill question matters for 2027. When prices eventually fall, the government will likely seek to rebuild the SPR, adding a new source of demand. Refilling 115 million barrels over a year would add roughly 315,000 barrels a day of demand, enough to slow the price decline the EIA forecasts.
For the forecast, the depleted SPR raises the upside risk from any new supply shock. It is one reason Brent's floor sits near $95 rather than lower. A market without a strategic cushion will react more violently to outages like Libya, and that asymmetry supports a higher risk premium.
The Fed and the Dollar: Why Oil Is Now a Rates Story
Oil and interest rates are locked in a feedback loop. The September flash PMI showed U.S. input costs rising at their fastest pace since October 2022, with fuel and transport costs cited as the main drivers. The 10-year Treasury yield hit 5.058%, its highest since July 2007, and the 2-year rose almost 10 basis points to 4.874%. The odds of an October Fed rate hike climbed above 53%.
The Fed is responding to oil-driven inflation. On September 16, the Fed raised the federal funds target by 25 basis points to a 3.75% to 4.00% range, its first increase since July 2023, and signalled another could come this year. Rate hikes are the central bank's response to an energy shock feeding into broader prices. Each oil spike raises the probability of further hikes.
Higher rates have a two-way effect on crude. On one side, higher rates slow the economy over time, which reduces oil demand and eventually pushes prices lower. On the other side, higher rates strengthen the dollar, which makes oil more expensive for foreign buyers and weighs on prices. Both effects work against crude, but with a lag.
The dollar is already a headwind. The dollar index held near 100.56 and rose another 0.4% after the PMI to its strongest level since late July. The euro fell to 1.1401, near its lowest since late July. A stronger dollar raises the local-currency cost of oil for importers in Europe and Asia, which curbs demand at the margin.
The equity market reflects the tension. The S&P 500 fell 0.54% and the Nasdaq Composite dropped 1.06% on Wednesday as yields surged. Falling stocks and a strong dollar are typically bearish for oil. That crude rose anyway shows how much weight the Libya supply shock carried.
The macro link also runs through demand. Higher prices are already curbing gasoline and distillate demand, which is the adjustment mechanism the market relies on to balance supply shortfalls. If the Fed's hikes add to that demand destruction, the oil market could rebalance faster than the EIA expects.
For the forecast, the Fed caps oil's upside. A Brent move above $105 would push inflation expectations higher, raise October hike odds toward 70% and strengthen the dollar, all of which would eventually pull oil back. A dovish Fed surprise would weaken the dollar and give crude more room to rally. The Fed's October 28-29 meeting is a key date for the oil market.
Energy Equities and Shipping: Natural Gas Leads, Tankers Wobble
Energy stocks are among the few winners on a down day for equities. Energy was among the few sectors in positive territory on Wednesday, even as the S&P 500 fell 0.54%. Natural gas producers led the group.
The standout movers show where investors see the tightest supply. Venture Global, the LNG exporter, jumped $0.74, or 5.73%, to $13.65, giving it a market value of $34.1 billion. Antero Resources gained $1.32, or 3.83%, to $35.74. Sasol rose 3.01% to $14.20, carrying a 52-week gain of 122.78%. LNG and gas exposure is benefiting from the same Middle East disruptions that support crude, with Hormuz carrying a large share of global LNG trade.
Tanker stocks show the other side of diplomacy. On Tuesday, as Iran talks raised hopes for Hormuz reopening, TORM fell 6.71% to $34.63 and Okeanis Eco Tankers dropped 6.16% to $77.54. Tanker rates spike when routes are disrupted and ships must take longer paths or wait for passage. A diplomatic opening that normalizes Hormuz traffic would reduce those rates, which is why tanker stocks sold off on the talks.
The tanker moves are a useful signal for the whole complex. Okeanis carries a 52-week gain of 157.78% and TORM a 52-week gain of 57.41%, reflecting the windfall from the war's shipping disruption. If tanker stocks continue to slide, the market is pricing a return to normal flows. If they rebound, the market is pricing a longer disruption.
The integrated majors and refiners sit between the extremes. Refiners benefit from wide diesel margins, and a U.S. diesel export ban would hurt U.S. refiners with export exposure while helping foreign refiners. Integrated producers benefit from high crude prices but face the prospect of lower prices in 2027 under the EIA's forecast.
Energy's weight in the market limits its influence. Even a strong energy sector cannot offset a 1% decline in the Nasdaq when technology dominates index weights. But energy's outperformance on Wednesday shows that investors still treat oil supply risk as real, even as they price de-escalation.
For the forecast, energy equities offer a lever on the oil view. A Libya outage that persists and Iran talks that stall would favour producers, LNG exporters and tanker owners. A Hormuz reopening deal would hit tankers first, then producers. Gas-weighted names like Venture Global and Antero have the most defensive profile because global LNG tightness persists regardless of the Iran outcome.
Technical Map: WTI $88 to $95, Brent $95 to $105
The charts show crude consolidating after a sharp run. Brent has risen 10.24% over the past month and 46.60% over the past year. WTI has gained 12.45% over the past month and 53.49% over the past year. The five-session decline into Tuesday was a pullback inside that uptrend, and Wednesday's bounce is the first test of whether the uptrend resumes.
For WTI, resistance sits in layers. The first level is $91.92, Wednesday's mid-morning high. A close above $92 would confirm the reversal. The next level is $95, a round number the market traded near earlier in the week. Above that, the path opens toward the upper end of the recent range.
WTI support is well defined. Tuesday's close at $90.52 is the first line. Wednesday's low at $89.64 is the second, and a break below it would mark a lower low and signal the Libya bounce has failed. Below $89.64, $88 is the next level, then $85, a level that would require a clear diplomatic breakthrough to reach.
For Brent, $100 is the pivot. The benchmark closed below $100 for the first time since early September during the five-day decline, and Wednesday's rally took it back above $101. Holding above $100 keeps the supply-risk premium in place. A close back below $99 would suggest the Libya bounce has faded and put $95 in play.
Brent resistance sits at $105. A move above that level would require a combination of extended Libya outages, stalled Iran talks and continued inventory draws. With the EIA forecasting a $90 average for the rest of the year, sustained prices above $105 look unlikely without a new escalation.
The WTI-Brent spread near $9.70 is also a technical signal. A widening spread reflects global tightness exceeding U.S. tightness. If the spread narrows, either Brent is falling on Middle East relief or WTI is rising on U.S. draws. The spread's direction will signal which market is driving prices.
The trading ranges into October are clear. WTI between $88 and $95, Brent between $95 and $105. A break outside those ranges depends on Iran. Inside those ranges, Libya headlines, weekly EIA data and the Fed will drive day-to-day swings of 1% to 3%.
Oil Price Forecast: $95 to $105 Brent, $88 to $95 WTI, Verdict
The forecast breaks into three scenarios, each keyed to the Iran track, the duration of the Libya outage and the pace of inventory draws.
The base case is a range between $95 and $105 for Brent and $88 and $95 for WTI into late October. Iran talks continue without a deal before the midterms, the Libya outage lasts days to weeks, Hormuz flows improve gradually and the Saudi East-West pipeline adds capacity. U.S. crude stocks stay near their five-year average while distillates stay tight. Brent averages near $100, above the EIA's $90 second-half forecast but inside its range of outcomes. This path carries a 50% probability.
The bull case targets $110 Brent and $98 WTI, 8% and 7% above current levels. It requires Iran talks to break down or military escalation to disrupt Hormuz again, the Libya outage to extend into October or spread to other fields, and a U.S. diesel export ban that tightens global product markets. The depleted SPR at 285 million barrels would limit the government's ability to cap prices. This path carries a 25% probability.
The bear case targets $90 Brent and $85 WTI, 11% and 8% below current levels. It requires a U.S.-Iran framework deal that reopens Hormuz fully, a quick resolution of the Libya outage, and repeated U.S. crude builds like Wednesday's 2.969 million barrels. A stronger dollar and an October Fed hike would add demand pressure. This path aligns with the EIA's projected decline toward $77 by the second quarter of 2027. This path carries a 25% probability.
Levels to trade for WTI: resistance at $91.92, $92, $95 and $98. Support at $90.52, $89.64, $88 and $85. For Brent: resistance at $101.61, $105 and $110. Support at $100, $99.01, $95 and $90.
The verdict on oil for September 23 is neutral with an upside tilt in the short term and a bearish tilt into 2027. The Libya outage at El Sharara, which removed roughly a third of the country's output, snapped a five-day decline and lifted WTI to $91.92 and Brent back above $101. The EIA's 2.969 million-barrel crude build and a 2.266 million-barrel Cushing refill cap WTI's upside, while a 428,000-barrel distillate draw and record diesel prices keep the product market tight. Global inventories are still falling at 3.0 million barrels a day, the SPR sits at 285 million barrels and Iran's conditions remain far from Washington's. Diplomacy, rising Hormuz flows and the Saudi East-West pipeline set the ceiling. Buy dips toward $89.64 WTI and $99 Brent while the war keeps Gulf supply constrained, and trim exposure on rallies toward $95 WTI and $105 Brent, where the Fed, the dollar and an eventual Iran deal cap the upside.