Brent ($103.60) Heads for 14% Monthly Gain as Diesel Squeeze Beats the SPR — $110 in Reach Above $105
Heating oil futures jumped 4.20% to $5.104 a gallon as the Brent-WTI spread widened to $12.29 | That's TradingNEWS
Key Points
- WTI rose 2.16% to $91.31 and Brent 1.00% to $103.60 after the EIA reported a 2.3 million-barrel distillate draw.
- U.S. distillate inventories sit 14% below the five-year average, pushing retail diesel to a record $6.53 a gallon.
- The SPR has fallen below 284 million barrels, its lowest since 1982, as Washington offers another 40 million barrels.
Crude oil is closing out the third quarter with the physical market tighter than the headline inventory data suggests. November West Texas Intermediate futures traded at $91.31 a barrel late Wednesday morning, up $1.93 or 2.16% from Tuesday's settlement of $89.38. Brent crude traded at $103.60, up $1.03 or 1.00%. The rally came one day after the U.S. Department of Energy offered up to 40 million barrels from the Strategic Petroleum Reserve, a move that briefly pushed WTI below $90 and Brent toward $102 on Tuesday.
The refined-product market tells the real story. Heating oil futures jumped 4.20% to $5.104 a gallon and RBOB gasoline gained 2.96% to $3.375. The Energy Information Administration's weekly report, released at 10:30 a.m. ET, showed distillate inventories falling 2.3 million barrels to a level 14% below the five-year average for this time of year. Retail diesel sits at a record $6.53 a gallon. Crude stocks rose 900,000 barrels, but that build was swamped by the drain in finished fuel.
The monthly scorecard shows how much the war has moved prices. Brent is headed for a monthly gain of around 14%, its biggest climb since July. WTI is on track for a gain of roughly 4%. The spread between the two benchmarks has widened to $12.29, its widest in four months, as the Middle East disruption hits waterborne crude far harder than landlocked U.S. barrels.
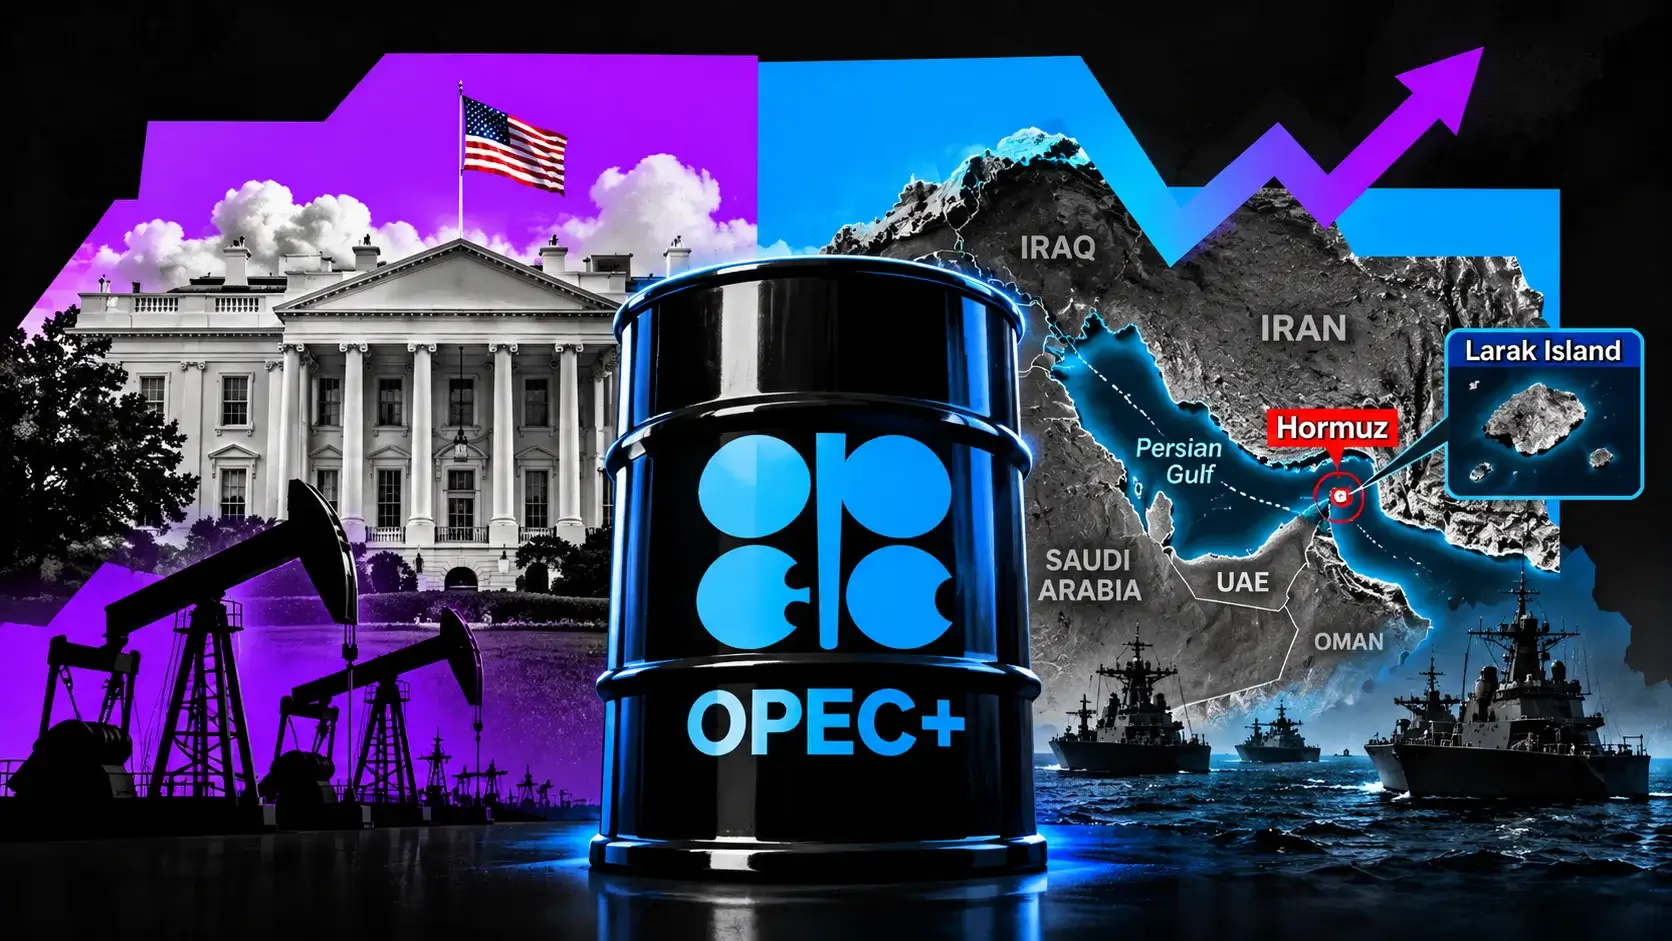
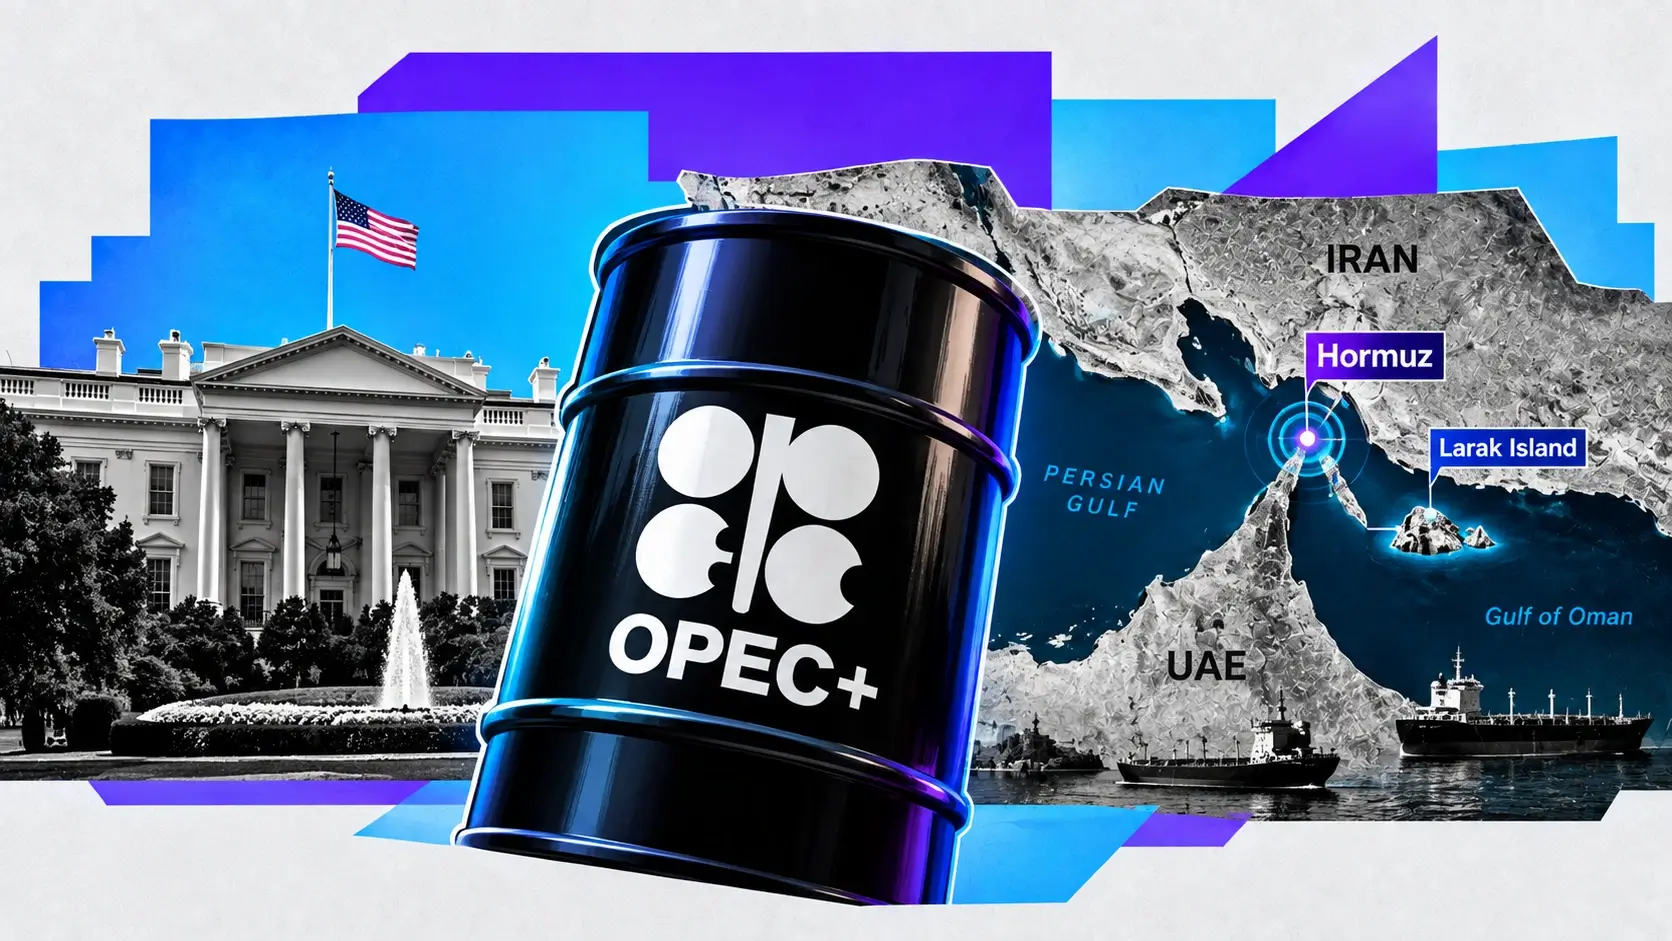
The backdrop is a seven-month war with Iran that has constrained flows through the Strait of Hormuz. Before the war began in late February, Brent traded near $72. It spiked above $115 in late March and has not traded sustainably below $84 since.
The thesis for this forecast is direct. The oil market is split between a crude surplus in the United States, where inventories sit 2% above average and Washington keeps releasing emergency barrels, and a global product shortage driven by lost Middle East refining and export capacity. That split keeps Brent anchored above $100 and pushes diesel prices to records. Brent should hold a $100 to $108 range in October with an upward bias, while WTI trades between $88 and $95. A break above $105 in Brent opens $110. A close below $100 would signal the supply recovery is winning.
The Session Map: From $89.38 to $91.31 in One Morning
Wednesday's trade moved through three distinct phases, and the product market led each one.
The Asian session opened the rebound. Brent futures rose $1.14 or 1.11% to $103.73 in Singapore trading, while WTI gained 34 cents or 0.38% to $89.72. The move reversed part of Tuesday's decline, when the SPR announcement and news of recovering Saudi exports knocked prices lower.
The European and early U.S. session extended gains. By 10:22 a.m. ET, Brent traded at $103.34, up $0.75 or 0.73% on the day and roughly $2 above its level a week earlier. WTI traded at $90.76, up $1.38 or 1.54%, but still $1.25 below where it stood a week ago. That divergence sums up the month: global crude prices climbing, U.S. crude lagging.
The EIA release at 10:30 a.m. ET triggered the third phase. The 900,000-barrel crude build came in close to the 1.019 million-barrel build that the American Petroleum Institute reported on Tuesday, so the crude number delivered no surprise. The product numbers did. The 2.3 million-barrel distillate draw and 1.7 million-barrel gasoline draw sent heating oil futures up 4.20% and gasoline futures up 2.96%. Crude followed the products higher. WTI extended to $91.31, up 2.16%, and Brent held $103.60.
Other grades confirmed the pattern. WTI Midland, the Permian Basin export grade, traded at $92.54, up 2.04%. Murban, the Abu Dhabi benchmark, traded at $114.60, down $2.31 or 1.98%, a sign that the Middle Eastern premium eased as Saudi export routes reopened. The OPEC basket traded at $111.80 as of its last update two days ago.
The session defines the near-term levels. For WTI, support sits at Tuesday's $89.38 settlement and the $89 area, with resistance at $92 to $93. For Brent, support sits at $102 and the psychological $100 level, with resistance at $105, the level Brent failed to hold earlier this month when Saudi Arabia shifted crude exports.
The EIA Report: A Crude Build Hides a Distillate Crisis
The Energy Information Administration's weekly data for the week ending September 25 shows a market split in two.
Commercial crude inventories rose 900,000 barrels to 427.3 million barrels, now 2% above the five-year average for this time of year. The prior week brought a much larger build of 2.969 million barrels to 426.4 million barrels, against expectations for a 600,000-barrel draw. In that week, crude stocks at the Cushing, Oklahoma, delivery hub rose 2.266 million barrels to 23.7 million barrels, and refinery utilization fell 2.8 percentage points to 94%.
Two weeks of crude builds totaling 3.87 million barrels explain why WTI has lagged Brent. The United States has more crude than it needs at current refinery runs, and the SPR releases add to that supply. U.S. crude sits in storage while the rest of the world scrambles for barrels.
Refined products tell the opposite story. Gasoline inventories fell 1.7 million barrels, matching the prior week's 1.7 million-barrel draw, for a two-week decline of 3.4 million barrels. Gasoline production averaged 9.5 million barrels per day.
Distillates, which include diesel and heating oil, fell 2.3 million barrels. Distillate production dropped to 5.0 million barrels per day. Inventories now sit 14% below the five-year average, a shortage that shows up directly at the pump.
Demand is running hot. Total products supplied, a proxy for U.S. oil consumption, averaged 20.8 million barrels per day over the past four weeks, up 2.1% from the same period last year. Gasoline demand averaged 8.7 million barrels per day. Distillate demand averaged 3.8 million barrels per day, up 5.2% year over year.
That distillate demand growth matters. Rising diesel consumption alongside falling diesel production is the fastest way to drain inventories. With distillate stocks already 14% below average heading into winter heating season, the product market has no cushion.
The report reinforces the forecast. Crude oil itself is not scarce in the United States. Refined fuel is scarce everywhere. As long as that gap persists, refiners will keep bidding for crude to run, which supports prices even as crude inventories build.
Diesel at $6.53: The Product Crack That Drives Crude
The diesel market has become the most important price signal in the oil complex, and its strength explains why crude keeps rallying through bearish inventory data.
Retail diesel prices in the United States hit a record $6.53 a gallon this week, above the $6.50 level that drew political attention in Washington. The White House ruled out a diesel export ban even as prices surged, after the oil industry warned that restrictions would backfire and worsen the global fuel crisis. President Trump had appeared to back an export ban earlier in September as fuel prices became a midterm election issue.
Heating oil futures, the benchmark for diesel, traded at $5.104 a gallon on Wednesday, up 4.20%. Converted to a per-barrel basis at 42 gallons per barrel, that equals $214.37 a barrel. Against Brent at $103.60, the implied diesel crack spread, the margin refiners earn turning crude into diesel, stands at $110.77 a barrel. That is an extraordinary margin by any historical standard.
Gasoline shows a smaller but still elevated spread. RBOB futures at $3.375 a gallon equal $141.75 a barrel. Against WTI at $91.31, the gasoline crack stands at $50.44 a barrel.
The supply side explains the squeeze. The war has shut in Middle East refining and export capacity, cutting off diesel supply that normally flows to Europe and Asia. Russia extended its diesel export ban through October 31, removing another major source. European gas prices hit their highest level since 2022 earlier this month, raising refinery operating costs in Europe.
The squeeze feeds directly into inflation. U.S. energy goods and services prices rose 2.3% in August, according to the personal consumption expenditures report released Wednesday. German energy inflation reached 14.9% in September, and eurozone energy inflation hit 14.3% in August. Truckers face operating costs 40% to 50% higher than in 2019.
For the crude forecast, the crack spread is the transmission mechanism. When refiners can earn $110 a barrel making diesel, they run their plants as hard as possible and pay up for crude. That bid supports Brent above $100 even when crude inventories build.
Washington's 40-Million-Barrel SPR Release and the 1982 Low
The U.S. government's latest emergency release briefly knocked prices lower on Tuesday, but its limits are becoming clear.
On Tuesday, the Department of Energy issued a request for proposals to release up to 40 million barrels from the Strategic Petroleum Reserve on a loan basis. The release takes the form of an exchange, effectively a loan that companies must repay with interest. The department said the program will return about 200 million barrels to the reserve over the next year, roughly 20% more than the amount released. Bids are due October 6.
This tranche completes the U.S. share of a coordinated drawdown. In March, President Trump authorized the release of 172 million barrels over 120 days, part of an International Energy Agency agreement in which roughly 30 member nations committed to put 400 million barrels on global markets. The United States also urged European nations to release more of their own reserves, including emergency diesel stocks.
The SPR has fallen to its lowest level in more than four decades. The reserve's inventory has dropped below 284 million barrels, a level not seen since 1982. Before the war began, the reserve held roughly 415 million barrels. At 284 million barrels, the SPR has lost 131 million barrels, or 31.6% of its pre-war level. Federal law sets the minimum at 252 million barrels, and the operational minimum sits between 250 million and 300 million barrels. A full 40-million-barrel release would push the reserve toward that floor.
Demand for the barrels has been weak. When the Department of Energy first tendered the same 40 million barrels in June, companies agreed to take only 500,000 barrels, leaving the department to put the offer back on the market. The loan structure requires companies to return more oil than they take, which makes the barrels less attractive when prices are expected to stay high.
Energy Secretary Chris Wright has signaled that another drawdown after this one is unlikely. That matters for the forecast. The SPR has been Washington's main tool for capping prices during the war. With the reserve near its legal floor and this tranche completing the U.S. commitment, that tool is running out.
For traders, the October 6 bid deadline is a near-term catalyst. Weak uptake would confirm that the SPR can no longer move the market.
Middle East Supply: Exports Recover, but Shut-Ins Persist
The biggest bearish force in the oil market is the gradual recovery of Middle East exports, and it explains why prices have not pushed higher despite the product squeeze.
Saudi Arabia resumed crude exports through its East-West pipeline at around half of its capacity and restarted tanker loadings from its Red Sea port of Yanbu on Tuesday. The pipeline gives Saudi Arabia a route to market that bypasses the Strait of Hormuz, the chokepoint through which roughly a fifth of global oil flows. Aramco's shift of exports toward the Red Sea sent Brent below $105 earlier this month.
Export data shows the recovery. The 10-day average of crude exports from the Middle East has recovered to 17.5 million barrels per day, equivalent to 98% of pre-war levels. Gulf oil exports climbed back to 23.3 million barrels per day last week, in line with their 2025 average, as exports doubled in September. A steady flow of crude also appears to be moving through the Strait of Hormuz on vessels transiting covertly. Estimates of Hormuz flows diverge sharply across forecasters, which adds uncertainty to any supply projection.
The recovery is incomplete. The EIA's September Short-Term Energy Outlook estimated that crude production shut-ins averaged 6.7 million barrels per day in August, up from 5.0 million barrels per day in July. The agency assumes Middle East flows remain constrained through the fourth quarter, with shut-in production averaging 5.7 million barrels per day. It estimated that global inventories fell 3.9 million barrels per day in the second quarter and will fall 3.0 million barrels per day in the third quarter and 1.7 million barrels per day in the fourth.
Those inventory draws matter more than export recovery headlines. Even with exports near pre-war levels, the world spent six months drawing down stockpiles at a record pace. Rebuilding those inventories will take months of surplus, which keeps prices elevated.
The EIA forecast Brent to average $90 in the second half of 2026, then fall to $77 by the second quarter of 2027 and $67 in the second half of 2027 as shut-in production returns. Brent has run well above that $90 path, trading near $103.60 today.
For the forecast, Middle East export recovery caps the upside, while inventory depletion props up the floor.
Iran and Hormuz: The Risk Premium That Refuses to Fade
Geopolitical risk remains the swing factor for oil prices, and this week's headlines kept the premium in place.
On Tuesday, unknown projectiles struck three vessels in the Strait of Hormuz, including a crude oil tanker and an LNG tanker, according to the United Kingdom Maritime Trade Operations Centre. A spokesperson for Iran's Revolutionary Guard Corps said the war would end only when Washington admits defeat and leaves. Iran published a letter urging Americans to protest against President Trump. Iran has also warned that no energy infrastructure in the region will be safe if it cannot sell its own oil.
Diplomacy has stalled. Iran received a U.S. response on Wednesday to its proposed seven-day ceasefire plan, presented last week. Talks between the two sides revived a June plan for ending the Hormuz standoff. Qatar said it hopes shuttle diplomacy can deliver a breakthrough. Qatar itself extended its LNG force majeure as the Hormuz crisis drags on.
President Trump denied reports that he was willing to provide sanctions relief and release frozen Iranian funds in exchange for concrete steps on Iran's nuclear program. Those reports had sent crude well off its highs on Monday. The denial on Wednesday pushed prices back up, with oil climbing as Trump ruled out easing Iran sanctions.
The war's price history shows how quickly headlines move the market. Brent finished March 3 at $81.49 after the war began, then surged above $115 by late March as Iran-backed Houthi militants joined the conflict. It traded near $84 in early August on ceasefire hopes, then climbed back above $100 as attacks on shipping resumed in late August.
The risk premium works in both directions. A credible ceasefire that reopens Hormuz to normal traffic could knock $10 or more off Brent within days, as the market prices in the return of shut-in production. A major attack on Gulf energy infrastructure, such as the Saudi pipeline or Yanbu port, could push Brent back toward $115.
For the forecast, the premium is unlikely to disappear in October. Diplomatic progress has been slow, attacks continue, and Iran has signaled it will target energy infrastructure if pressed. That keeps a floor under Brent near $100.
The $12.29 Brent-WTI Spread: Two Markets, One War
The gap between Brent and WTI has become one of the most telling signals in the oil market, and it reflects how differently the war affects global and U.S. crude.
At Wednesday's prices of $103.60 for Brent and $91.31 for WTI, the spread stands at $12.29 a barrel, its widest level in four months. Brent is on track for a monthly gain of around 14%, while WTI is set to rise roughly 4%.
The divergence reflects geography. Brent prices waterborne crude that competes directly with Middle East supply. When Gulf exports fall or shipping routes close, buyers in Europe and Asia bid up Brent-linked barrels. WTI prices crude delivered at Cushing, Oklahoma, deep inside the United States, where domestic production and SPR releases keep supply ample.
The U.S. inventory data confirms the split. Commercial crude stocks sit 2% above the five-year average at 427.3 million barrels, and Cushing stocks rose 2.266 million barrels to 23.7 million barrels two weeks ago. The SPR releases add to U.S. supply. None of that crude helps a refiner in Rotterdam or Singapore unless it is exported.
The spread has swung wildly during the war. On March 18, the difference between Brent and WTI hit its widest in 11 years. At another point, WTI briefly traded above Brent, with the gap in WTI's favor the widest since 2009, when Iranian restrictions in Hormuz sent WTI up more than 3% to $97.87 while Brent finished at $95.92.
The current wide spread creates an arbitrage. At $12.29 a barrel, U.S. exporters can ship WTI to Europe and Asia at a healthy margin after freight costs. Higher freight costs have pushed more U.S. energy exports toward Europe. Rising U.S. crude exports would gradually drain domestic inventories and narrow the spread.
For the forecast, the spread matters for which benchmark carries the upside. If the Middle East disruption persists, Brent will outperform WTI. If U.S. exports rise and domestic inventories fall, WTI will catch up. The spread at $12.29 suggests WTI offers more room to rise as the arbitrage closes.
OPEC+, China and India: The Demand and Supply Crosscurrents
Beyond the Middle East war, three other forces shape the oil balance heading into the fourth quarter.
OPEC+ is expected to keep its oil production quotas unchanged at its next meeting. With Middle East flows constrained by the war, the group's quota levels matter less than usual, since many members cannot ship their full allocations through Hormuz. OPEC crude production can only increase once normal flows resume through the Strait in both directions.
China's demand is softening. Forecasters cut China's fourth-quarter crude import estimates by 400,000 barrels per day this week. China's LNG imports are set for a second straight monthly drop. China's thermal coal prices surged to a three-year high, a sign that Chinese buyers are substituting coal for more expensive oil and gas where possible. Weaker Chinese buying removes one source of demand pressure on Brent.
India is moving the other way. India boosted its Middle East oil imports and cut Russian flows, as the United States threatened 100% tariffs over Russian oil purchases and a new U.S. sanctions law threatened India's Russian oil trade. Indian demand for Gulf crude supports Brent-linked grades. The oil rally has also hit India's markets, with foreign investors pulling $3.2 billion from Indian equities as oil prices climbed.
The combined effect is roughly neutral for the global balance. Chinese weakness offsets Indian strength, and OPEC+ is sidelined by the war. That leaves the Middle East supply recovery and the product squeeze as the two dominant drivers.
Non-OPEC supply offers some relief. Norway's liquids production rebounded by nearly 100,000 barrels per day, though it still trails 2025 levels. TotalEnergies is targeting 3% annual oil and gas growth through 2030. U.S. shale continues to consolidate, with BP eyeing a bigger shale footprint after talks with Devon Energy. LNG Canada approved phase two to double its export capacity.
For the forecast, these crosscurrents limit the upside. Without Chinese demand growth, Brent struggles to push much past $110 even with Middle East disruptions. They also limit the downside, because Indian buying and depleted global inventories keep a floor near $100.
The Macro Link: Oil, the Fed and the Dollar
Oil prices now sit at the center of the Federal Reserve's inflation fight, and the feedback loop between crude and interest rates shapes both markets.
Wednesday's personal consumption expenditures report showed core inflation at 3.0% annually, below the 3.3% forecast, while headline inflation came in at 3.4%. Energy goods and services rose 2.3% on the month in August. The gap between headline and core inflation comes almost entirely from energy, which means oil prices directly determine how far headline inflation sits above the Fed's 2% target.
The Fed raised rates on September 16 to a 3.75% to 4.00% range, its first hike since 2023, citing inflation driven by the energy shock. Rate futures priced a 47% chance of another hike in October before Wednesday's data, then cut that to 37% after the softer core reading. The Fed tends to look through energy-driven inflation spikes, but only if they do not spill into wages and services.
Oil price moves can shift that calculation. A move in WTI toward $95 or $100 would push headline inflation higher and raise the risk that energy costs feed into broader prices. That would revive October hike odds and push Treasury yields higher. The 10-year Treasury yield touched 5.29% on Tuesday, its highest since 2007, driven in part by oil-fueled inflation concerns.
The dollar adds another layer. The dollar index climbed from below 99 at the start of September to 101.40 by Tuesday. A strong dollar usually weighs on oil, since crude is priced in dollars and becomes more expensive for foreign buyers. That the oil rally has continued despite a rising dollar shows how tight the physical market has become.
Read More
-
Yen Stalls at 160 Despite a 3% JGB and Tokyo Core CPI at 2.0% — Intervention Sits at 164, Friday's Payrolls Decide
02.09.2026 · TradingNEWS ArchiveEnergy
-
MU ($1,076) Faces the $56.64B Guidance Test at 6.8x Forward Earnings — $1,255 Record in Reach
30.09.2026 · TradingNEWS ArchiveStocks
-
XRP-USD ($1.51) Faces the 1B XRP Escrow Test With $1.79B in ETF Inflows — $1.66 in Reach Above $1.60
30.09.2026 · TradingNEWS ArchiveCrypto
-
Gold ($4,212) Bounces From $4,145 Low on Softer Inflation — $4,350 in Reach as Central Banks Buy
30.09.2026 · TradingNEWS ArchiveCommodities
-
S&P 500, Nasdaq and Dow Rally as Core PCE Drops to 3.0%, MRNA Slides 6.56% and Micron Looms
30.09.2026 · TradingNEWS ArchiveMarkets
-
GBPUSD (1.3270) Turns Higher as BoE Hike Odds Hit 85% and Fed Bets Fade — 1.3345 in Reach
30.09.2026 · TradingNEWS ArchiveForex
The equity market reflects the energy tension. The S&P 500 rose 0.56% on Wednesday as bond yields eased after the inflation data. Energy stocks have traded unevenly, pulled between high crude prices and fears that elevated fuel costs will slow the economy.
For the forecast, the macro link cuts both ways. Higher oil prices raise the odds of Fed hikes, which strengthen the dollar and slow growth, eventually weighing on demand. That feedback loop acts as a ceiling on how far oil can rally before it begins to destroy demand.
Technical Map: Brent $100 Floor, $105 Pivot, $110 Overhead
Oil's chart structure defines clear levels for both benchmarks heading into October.
For Brent, the psychological $100 level is the key floor. Brent fell near $102 on Tuesday after the SPR announcement but held above $100, and bounced to $103.60 on Wednesday. A daily close below $100 would signal that the supply recovery has overtaken the product squeeze and open a move toward $96, a 7.3% decline from current levels.
The first resistance for Brent sits at $105. Brent failed to hold above that level earlier in September when Saudi Arabia shifted exports to the Red Sea. A close above $105 requires a 1.4% gain and would open the path toward $110, a 6.2% gain. Above $110, the late-March peak above $115 marks the war's high-water mark.
For WTI, Tuesday's $89.38 settlement defines first support, with the $89 area just below. WTI dipped toward $89 on Tuesday after the SPR news and bounced. A close below $89 would open $85, a 6.9% decline. First resistance sits at $92 to $93, where WTI traded a week ago, $1.25 above Wednesday's early level. A close above $93 opens $95, a 4.0% gain.
Monthly momentum favors buyers. Brent's 14% September gain is its largest monthly advance since July, and both benchmarks are on track for monthly and quarterly gains. Brent is up 48.57% from the same time last year.
The product charts lead crude. Heating oil's 4.20% jump on Wednesday to $5.104 a gallon shows where the pressure sits. As long as diesel stays above $5 a gallon on futures, refiners have every incentive to keep buying crude.
The Brent-WTI spread at $12.29 adds a technical signal. A narrowing spread would signal WTI catching up, while a widening spread would show Brent-specific tightness intensifying.
For traders, the risk-reward in Brent favors longs above $100 with targets at $105 and $110. A stop below $100 limits downside to 3.5%, while the first target offers 1.4% and the second 6.2%.
The Risk Ledger: Ceasefire, Demand Destruction, a Hot Dollar and the SPR Floor
Four specific risks could push oil prices below the key $100 Brent and $89 WTI levels.
The first is a ceasefire. Iran has proposed a seven-day ceasefire, and the United States sent a response on Wednesday. Talks revived a June plan for ending the Hormuz standoff. A credible agreement that reopens Hormuz to normal traffic would release shut-in production, which the EIA estimated at 6.7 million barrels per day in August, and could knock $10 or more off Brent within days. The EIA's forecast of $77 Brent by the second quarter of 2027 shows where prices head once flows normalize.
The second risk is demand destruction. Retail diesel at $6.53 a gallon and gasoline crack spreads above $50 a barrel squeeze consumers and businesses. U.S. consumer confidence fell to a 12-year low in September. Truckers face costs 40% to 50% above 2019 levels. China has already cut its fourth-quarter crude import forecasts by 400,000 barrels per day. At some price level, high fuel costs reduce consumption enough to rebalance the market.
The third risk is the dollar and interest rates. If Friday's September payrolls report comes in hot, Fed hike odds would climb back above 47%, pushing the dollar and Treasury yields higher. A stronger dollar makes oil more expensive for buyers outside the United States, and higher rates slow economic growth and oil demand.
The fourth risk runs the other way for WTI. The SPR sits near 284 million barrels, close to the legal 252-million-barrel floor. If this 40-million-barrel release draws strong bids by October 6, it adds supply to the U.S. market and pressures WTI. If it draws weak bids, as the June tender did when companies took only 500,000 barrels, it signals the SPR has lost its power to cap prices.
A fifth risk is an escalation that sends prices sharply higher. An attack on the Saudi East-West pipeline or Yanbu port would remove the main bypass route around Hormuz. That scenario would push Brent back toward the late-March high above $115.
Oil Price Forecast and Verdict: Brent $100 to $108 With an Upward Bias, WTI $88 to $95
The verdict on oil is range-bound with an upward bias, led by refined products rather than crude itself. WTI trades at $91.31, up 2.16%, and Brent at $103.60, up 1.00%, after the EIA report showed distillate stocks falling 2.3 million barrels to 14% below the five-year average. Heating oil futures jumped 4.20% to $5.104 a gallon, and retail diesel sits at a record $6.53.
The bullish case rests on the product squeeze. The implied diesel crack spread of $110.77 a barrel gives refiners every reason to buy crude aggressively. Global inventories drew down at 3.9 million barrels per day in the second quarter and are projected to fall another 3.0 million barrels per day in the third quarter. Shut-in production still averaged 6.7 million barrels per day in August. The SPR has fallen below 284 million barrels, the lowest since 1982, and the current 40-million-barrel tranche completes Washington's commitment.
The bearish case rests on supply recovery. Middle East exports have climbed back to 98% of pre-war levels on a 10-day average. Saudi Arabia reopened its East-West pipeline and Yanbu loadings. U.S. crude inventories sit 2% above average at 427.3 million barrels. China cut its fourth-quarter import outlook by 400,000 barrels per day.
The balance points to Brent holding a $100 to $108 range in October. A daily close above $105 opens $110, a 6.2% gain. A close below $100 would target $96, a 7.3% decline. For WTI, the range runs from $88 to $95. A close above $93 opens $95, while a close below $89 opens $85. The $12.29 Brent-WTI spread suggests WTI has more room to catch up if U.S. exports rise.
Four triggers decide the path: the October 6 SPR bid deadline, any ceasefire progress on Hormuz, the weekly EIA distillate data, and Friday's payrolls report through its effect on the dollar and Fed odds.
The balance of evidence favors firm prices through October, with a global product shortage and depleted inventories overpowering the gradual recovery in Middle East exports, so as long as Brent holds $100 and diesel futures stay above $5 a gallon, the forecast calls for Brent to test $105 and WTI to push toward $93 to $95, with a ceasefire the single event that could break the floor.