WTI ($100) Drops 5% From $105 High as Hormuz Transfers Hit 2.7M bpd — Downside Toward Brent $95.63
Crude reversed from its highest close since May as Saudi Arabia targeted half pipeline capacity within days | That's TradingNEWS
Key Points
- WTI trades at $100.55 and briefly dipped below $100 after settling at $105.83 on Tuesday.
- Ship-to-ship transfers near Oman rose to 2.7 million bpd from 1.5 million bpd in August.
- U.S. crude inventories fell 640,000 barrels to 423.4 million against a forecast build.
West Texas Intermediate crude is trading at $100.55 per barrel, down 1.8% on the day, after briefly dipping below $100. Brent crude, the international benchmark, is down 2.6% at $103.05. During the European morning, October WTI traded between $100.39 and $102.47, and November Brent between $103.62 and $106.02. Both contracts are extending a second straight day of losses.
The retreat follows a violent spike. On Monday, October WTI settled at $101.39, up $1.34, after trading as high as $104.95. On Tuesday, WTI jumped 4.4% to settle at $105.83, its highest close since May 19, while Brent gained 2.9% to $108.75. On Wednesday, the move reversed: WTI fell 3.2% to $102.43 and Brent lost 2.7% to $105.83. From Tuesday's close to Thursday's price, WTI has shed $5.28, or 5.0%, and Brent has lost $5.70, or 5.2%.
The monthly gain is still large. Even after two days of selling, U.S. crude is up 17% for September. Prices had rallied more than 20% for the month at Tuesday's peak as fighting escalated in the Persian Gulf. Crude pushed back above $100 for the first time since July during last week's 8% weekly rise. On September 2, Brent settled at $95.63. The market has now retraced most of this week's spike, but not the month's.
The drivers of the decline are supply relief, not demand weakness. Saudi Arabia is aiming to restore half the capacity of its damaged East-West pipeline within days and return it to full operation within six weeks. Riyadh is also moving more crude to Asian refiners through ship-to-ship transfers just outside the Strait of Hormuz. China has privately asked Iran to help stop Houthi attacks on Saudi infrastructure. Each headline chipped away at the war premium built into prices on Tuesday.
The thesis for this forecast is simple. The paper market is pricing supply relief faster than the physical market can deliver it. Futures have already erased most of the week's spike, while U.S. crude inventories fell, freight costs hit records, and Chinese crude futures traded near $129 per barrel. The $100 line on WTI is where that disconnect gets tested. A daily close below $100 confirms the relief trade and opens a move toward Brent's pre-escalation level of $95.63. A reclaim of $102.47 puts Tuesday's $105.83 high back in play.
The broader market is cheering the decline. Lower crude pulled the 10-year Treasury yield down to 4.94%, helped the Nasdaq Composite climb 1.7%, and eased pressure on the Federal Reserve one day after its first rate hike since July 2023. Oil is now the single most important variable for inflation expectations, interest rates and equity direction. That puts every pipeline update and every Gulf headline at the center of global markets.
The East-West Pipeline: From Shutdown to Restart
The pipeline outage drove this week's spike. Saudi Arabia shut down its East-West pipeline after a drone attack launched from Iraq on September 11 damaged the line. Riyadh described the closure as a precautionary measure but did not provide a damage assessment or an estimate of how long the outage would last. The East-West pipeline carries crude from eastern oilfields to Red Sea export terminals, providing the main alternative route around the Strait of Hormuz.
The damage appeared severe. Satellite images showed fire-damaged structures and blackened ground at a pumping station along the pipeline following the attack. Independent assessments warned the pipeline could remain down for weeks based on significant damage to that pumping station. Two pumping stations along the pipeline were reported damaged, with the repair timeline unclear.
Saudi customers felt the impact immediately. Trade sources said the Saudis informed European customers that some September crude deliveries were cancelled, citing the pipeline closure. That news hit on Tuesday and helped send WTI 4.4% higher. Physical cargo cancellations are the strongest signal a supply shock is real, because they force refiners to find replacement barrels on short notice.
Washington pushed back against the worst-case view. U.S. Energy Secretary Chris Wright said on Tuesday that the pipeline outage is a "brief and temporary interruption" that "will be measured in days." He also said 18 million barrels of crude and petroleum products passed through the Strait of Hormuz earlier this week. His comments helped cap the rally and set up Wednesday's reversal.
The Saudi timeline gave traders a concrete path. Saudi Arabia is aiming to restore half of the pipeline's capacity within days and return it to full operation in six weeks. Half capacity within days would restore a large portion of the Red Sea export route quickly. Full operation in six weeks would take the pipeline into late October, which means the supply gap narrows sharply but does not close until after the Fed's October 27–28 meeting.
The reporting has not been fully consistent. Official statements point to a fast partial restart, while independent satellite assessments point to longer repairs. That gap is the core risk in the forecast. If the half-capacity restart arrives on schedule, the war premium keeps draining and WTI trades below $100. If the restart slips past September, supply fears return and Tuesday's $105.83 WTI close becomes a target again.
Saudi Arabia Reroutes Crude Through Hormuz
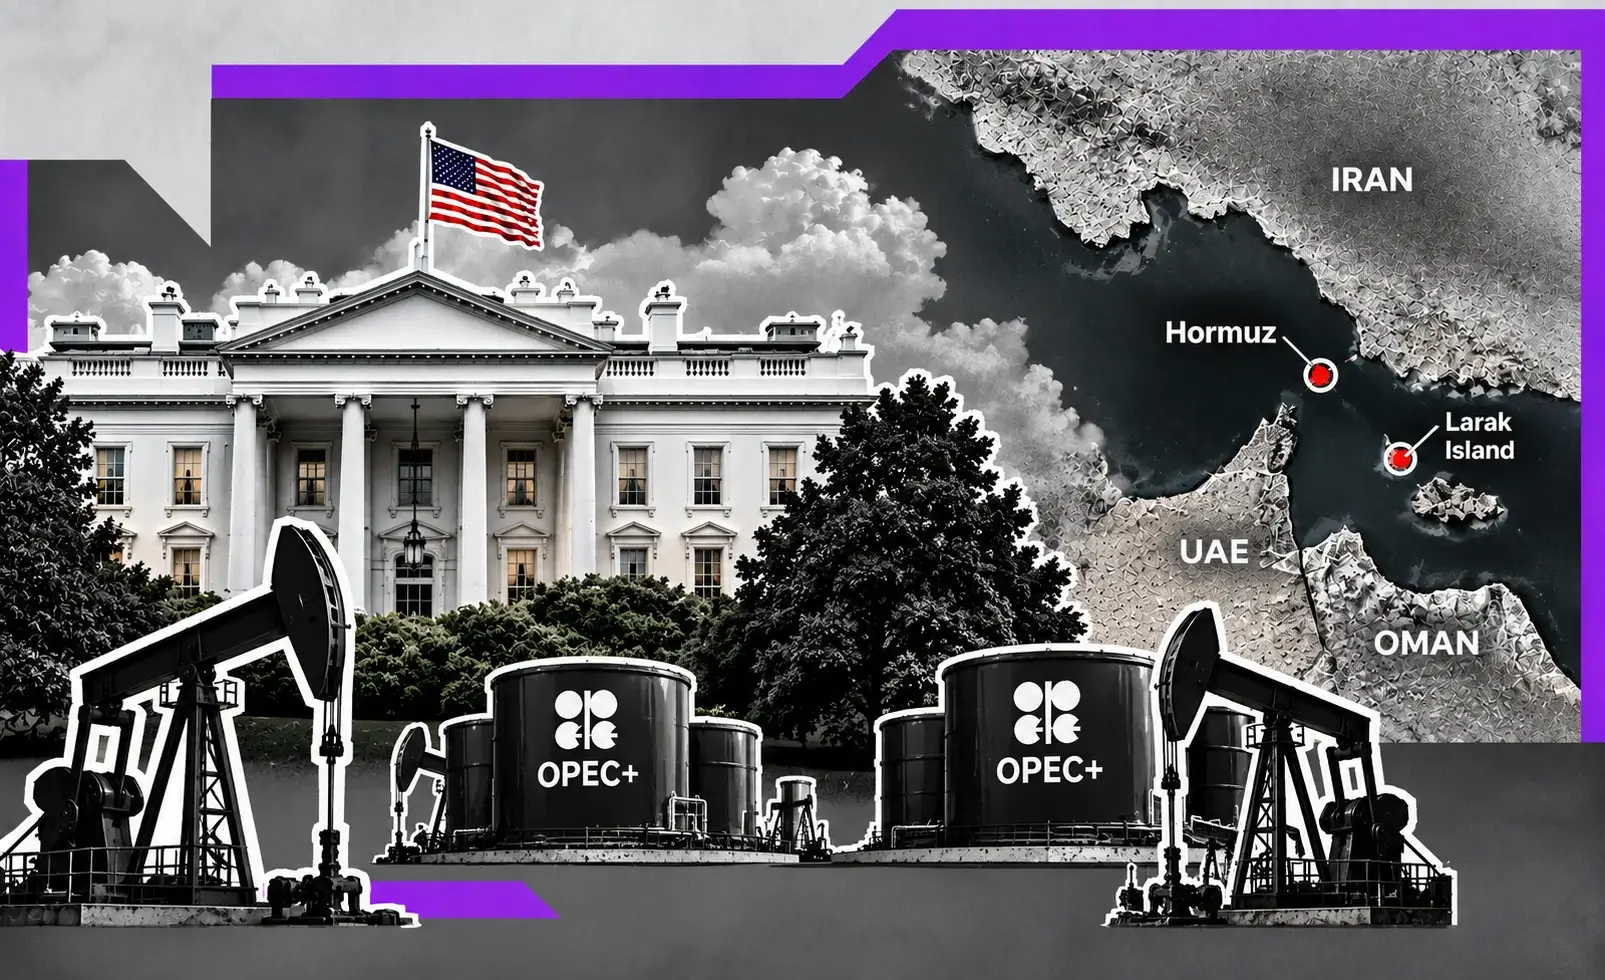
Saudi Arabia is building workarounds while the pipeline is down. The kingdom is making additional crude cargoes available to Asian refiners through ship-to-ship transfers just outside the Strait of Hormuz, near Oman's Sohar port. Shuttle vessels carry crude through Hormuz and load it onto tankers waiting outside the strait. That allows larger tankers to avoid sailing into the Gulf and exposing themselves to Iranian attack.
The volume is significant. Ship-to-ship transfers in the Gulf of Oman have risen to 2.7 million barrels per day, compared with 1.5 million barrels per day in August. That is an increase of 1.2 million barrels per day, or 80%. Saudi crude loadings at Mideast Gulf ports are up so far this month. The kingdom is compensating for the Red Sea outage by pushing more oil through the Gulf route it was trying to avoid.
The U.S. military is helping. Saudi Arabia has stepped up efforts to transport more crude through Hormuz with assistance from U.S. forces. That reduces the attack risk for shuttle vessels and supports the flow data. The 18 million barrels of crude and products that moved through Hormuz earlier this week show the strait remains open, even if contested.
The strait is not safe. At least two tankers came under attack in the Strait of Hormuz between Saturday and Tuesday, according to maritime incident reports. Gulf-Iran talks on Hormuz security scheduled in Oman were postponed on September 13. Rerouting through Hormuz concentrates more Saudi supply in the most dangerous shipping lane in the world. A successful attack on a shuttle tanker or a loading terminal would do more damage now than it would have in August.
Freight costs show the strain. The cost of shipping U.S. crude to Asia hit a record, with a very large crude carrier from the U.S. Gulf Coast to China costing $44.8 million on Wednesday, up from $39 million the day before. That is a 14.9% increase in one day. Tanker rates have topped $1 million per day for the first time as the Hormuz crisis creates a vessel shortage. Refiners are paying record prices to move crude from more distant suppliers.
The rerouting eases one bottleneck and tightens another. More Saudi crude reaching Asia reduces the shortfall that drove Tuesday's spike. Record freight costs raise the delivered price of every barrel that must travel longer distances. Futures fell this week on the rerouting news. Physical buyers still face the highest shipping costs on record. That is the gap between paper and physical markets at the center of this forecast.
Houthi Escalation and Red Sea Risk
Yemen's Houthis are expanding the conflict. The Iran-backed militants launched drones and ballistic missiles at the Saudi cities of Khamis Mushait, Abha and Taif this week. Sirens sounded in Abha and Khamis Mushait, and a projectile injured two people and damaged a mosque. The Houthi campaign against Saudi Arabia is now hitting population centers, not only energy infrastructure.
The militants are also gaining territory near a critical chokepoint. The Houthis seized the Greater and Lesser Hanish islands after taking Mokha and Mayun island, putting them within 32 kilometers of the U.S. base in Djibouti. Yemeni government forces are battling the Houthis in the strategic Kahbub mountains near the Bab al-Mandab strait. Control of positions near Bab al-Mandab gives the Houthis leverage over Red Sea shipping, the route Saudi crude takes after leaving the East-West pipeline's western terminals.
That creates a double threat to Saudi exports. The East-West pipeline exists to move crude to the Red Sea and bypass Hormuz. The Houthis now threaten both the pipeline itself, with drone strikes, and the Red Sea shipping lanes that carry its exports. Even when the pipeline returns to full capacity, its value as a Hormuz bypass depends on safe passage through Bab al-Mandab.
The humanitarian toll is rising. Since September 3, about 150 civilians have been killed and more than 200 wounded in Yemen, and 80,000 people have been displaced in two weeks. An intensifying ground war near the Red Sea raises the risk of attacks on commercial shipping as the Houthis seek leverage.
Diplomacy opened a new channel on Thursday. China has privately asked Iran to help stop Houthi attacks following an appeal from Saudi Arabia. China is the world's largest crude importer and has strong commercial ties to both Iran and Saudi Arabia. A Chinese request carries weight in Tehran, and it contributed to Thursday's decline in crude. U.S. and Houthi representatives also held talks over the weekend, with the Houthis saying they had no intent to attack U.S. or Israeli ships.
The Red Sea is the upside risk the market is discounting. Futures fell on diplomatic signals and pipeline progress. The Houthis' territorial gains near Bab al-Mandab have not reversed. Risk remains skewed toward a larger disruption if the pipeline outage extends past September or if Iran, the Houthis or other proxy groups escalate attacks. A single successful strike on a tanker in the Red Sea would likely send Brent back above $108.75.
U.S. Inventories Fall Against a Forecast Build
The weekly U.S. inventory report cut against the selloff. U.S. crude inventories fell by 640,000 barrels to 423.4 million barrels in the latest government data. That compared with an industry estimate of a 7.1 million-barrel build released a day earlier. The gap between a forecast 7.1 million-barrel increase and an actual 640,000-barrel draw is a 7.74 million-barrel swing toward tighter supply.
The draw was smaller than some expected, but the direction matters. A market pricing supply relief should see stocks build as imports arrive and demand softens. Instead, U.S. stockpiles fell. The data offered a counterweight to Wednesday's slide, but the pipeline headlines overwhelmed it. WTI still fell 3.2% on the day the draw was reported.
U.S. demand is holding up. August retail sales rose 1.2%, beating the 0.7% forecast, and control-group sales jumped 1.4%, the fastest pace since September 2024. Initial jobless claims fell to 196,000 in the week ended September 12, below the 208,000 forecast. A strong consumer and a tight labor market support fuel demand even at elevated prices. That limits how quickly inventories can rebuild.
Fuel prices show the demand pressure. The national average price of gasoline reached $4.32 per gallon on Monday, a 7-cent increase from the prior week. Diesel hit a record $6.23 per gallon on Monday, then climbed to a new record of $6.3103 on Wednesday. Diesel is up 70.5% from $3.7008 a year ago. Refined products are tighter than crude, and that gap is widening.
Refined-product markets face their own disruptions. Ukrainian drones hit Russia's Yaroslavl oil refinery overnight, and attacks on Russian refineries continue to disrupt global product markets. Russia is a major diesel exporter. Lost Russian refining capacity tightens diesel supply worldwide, which explains why diesel prices keep setting records even as crude futures fall.
The inventory picture supports the physical tightness thesis. U.S. stockpiles fell while analysts expected a build. Diesel set back-to-back records. Freight costs hit all-time highs. None of those data points are consistent with a market where supply fears are resolved. The futures decline reflects expectations of relief. The physical data reflects a market that still has not received it.
Global Prices Show Regional Scarcity
U.S. futures are falling while other regions pay record prices. Oil futures in Shanghai traded at $129 per barrel on Wednesday, above their $121.80 peak in the first weeks of the Iran war. Chinese refiners are scrambling for supply amid widening fears about the security of Middle East exports. Shanghai crude at $129 against Brent at $105.83 on the same day is a $23.17 premium.
That spread reveals where the shortage lives. China depends heavily on Gulf crude. When Saudi exports through the Red Sea stop and Hormuz becomes dangerous, Chinese buyers compete for fewer barrels. Saudi Arabia's ship-to-ship program near Oman targets exactly those Asian refiners. The rerouting is designed to close the Shanghai premium, and its success will show up in that spread before it shows up in Brent.
Europe felt the Saudi cancellations first. Some September Saudi crude deliveries to European customers were cancelled due to the pipeline closure. European refiners that relied on Red Sea-routed Saudi crude must now source barrels from the U.S., West Africa or Latin America. That shift explains part of the record freight costs for U.S. Gulf Coast cargoes and supports U.S. crude export demand.
European natural gas prices tracked the same stress. Front-month Dutch TTF gas futures hit a post-2022 high on Monday before falling 2.54% on Wednesday for a second straight decline. On Thursday, TTF stayed under €80 per megawatt-hour after finding support just above €76. Energy prices in Europe remain elevated enough that German machinery makers now expect 2026 production to fall 2% in real terms, and German industrial firm Bilfinger cut its sales forecast on Thursday, citing energy costs.
Other producers are adding supply. Argentina's oil output hit a record in July as the Vaca Muerta shale field expanded. Russia's Rosneft launched its Vostok Oil project, opening a new Arctic pipeline and shipping its first crude. Libya restored normal oil output after outages earlier this week, when the national oil company had suspended operations at two oilfields and a pumping station amid protests. Kazakhstan expects production to reach 96 million tonnes in 2028.
Non-Gulf supply cannot fill the gap quickly. New Arctic and South American barrels take weeks to reach Asian and European refiners, and record freight costs raise the delivered price. The global market is not short of oil in total. It is short of oil in the right places. That structure supports a premium in physical crude even as futures unwind the war-risk premium.
Read More
-
Yen Stalls at 160 Despite a 3% JGB and Tokyo Core CPI at 2.0% — Intervention Sits at 164, Friday's Payrolls Decide
02.09.2026 · TradingNEWS ArchiveEnergy
-
OKLO ($37) Trades at 2.35x Cash After $1B Share Sale Hit — Upside Toward $43.99 September High
17.09.2026 · TradingNEWS ArchiveStocks
-
XRP-USD ($1.2983) Defends $1.256 100-Day EMA as ETFs Hold 1.07B XRP — Upside Toward $1.40 Range Top
17.09.2026 · TradingNEWS ArchiveCrypto
-
Gold ($4,310) Recovers From $4,230 Low as 10-Year Yield Slips to 4.949% — Upside Toward $4,430 Range Top
17.09.2026 · TradingNEWS ArchiveCommodities
-
Nasdaq Rips 1.7%, S&P 500 Adds 1%, Dow Climbs 268 After Fed Hike; Fluence FLNC Plunges 22%
17.09.2026 · TradingNEWS ArchiveMarkets
-
GBP/USD (1.3381) Loses Rate Edge as Fed Hike Puts Bank Rate 12.5 bps Below — Downside Toward 1.33
17.09.2026 · TradingNEWS ArchiveForex
The Fed, Inflation and the Oil-Rate Link
Oil is now the Federal Reserve's biggest input. The FOMC raised rates by 25 basis points on Wednesday to a 3.75% to 4.00% target range, its first hike since July 2023. The policy statement removed prior language describing inflation as partly reflecting supply shocks in sectors including energy. The Fed will no longer look through oil-driven inflation.
That wording change links crude directly to interest rates. U.S. consumer prices rose 3.4% year over year in August. Energy has driven much of the monthly CPI increase this year. The Fed's median projection now shows rates at 4.1% at the end of 2026, implying one more hike, and 16 of 18 officials project additional tightening. Futures put a 50% probability on another hike at the October 27–28 meeting.
Crude falling below $100 changes that calculation. Lower oil pulls down inflation expectations, which reduces pressure on the Fed to keep hiking. If crude continues to move lower, markets may revise their expectations for future Fed policy quickly. That is why Thursday's oil decline sent the 10-year Treasury yield down to 4.94% from its 5.04% high earlier this week, the highest since 2007.
The dollar channel adds pressure. The dollar index touched 100.37 on Thursday, its strongest level since July 31, before easing to 100.08. A stronger dollar makes dollar-priced oil more expensive for foreign buyers and weighs on demand at the margin. The Fed hike lifted the dollar, which added to crude's decline on Wednesday.
Global central banks are tightening alongside the Fed. The European Central Bank raised its deposit rate to 2.50% on September 10, citing energy-driven inflation. The Bank of England held at 3.75% on Thursday but warned policy may need to tighten if the Middle East war remains unresolved. The Bank of Japan is expected to hike to 1.25% on Friday. Higher rates across major economies slow growth and energy demand over time.
The oil-rate feedback loop cuts both ways for the forecast. Lower crude eases inflation, softens rate expectations and supports growth, which eventually supports oil demand. Higher crude raises inflation, forces more hikes and slows growth, which eventually weakens demand. The Fed's decision to stop looking through energy shocks makes that loop faster. Every $5 move in WTI now moves Treasury yields, the dollar and equities within the same session.
Energy Equities and the Freight Warning
Energy stocks took the first hit. On Wednesday, S&P 500 energy stocks fell 2.97%, leading the index's losses. Diamondback Energy dropped 8.03% to $194.54, Occidental fell 6.54% to $59.37, ConocoPhillips lost 6.15% to $132.54, EOG Resources fell 5.73% and Devon Energy lost 5.63%. Chevron traded lower with oil prices ahead of the Fed decision. On Thursday, energy lagged the market again as crude extended its decline.
The producer selloff exceeded crude's move. WTI fell 3.2% on Wednesday. Diamondback fell 8.03%, more than 2.5 times that. Equity investors are pricing the end of the September windfall faster than futures are. Producers had rallied with crude through the month, and they are giving back gains quickly as the war premium drains.
The freight sector sits on the other side. J.B. Hunt fell 13.30% to $236.73 on Wednesday, the worst performer in the S&P 500, after its chief financial officer said higher diesel costs will drive a 5% to 10% sequential decline in third-quarter earnings. The company described fuel price swings as among the most abnormal it has seen. Diesel at a record $6.3103 per gallon is crushing transport margins even as crude falls.
Airlines face the same pressure. The NYSE Arca Airline Index fell 1.9% on Tuesday as higher crude prices increased attention on fuel costs. The Dow Jones U.S. Retail Index fell 2%, reaching its lowest close in more than a month, on concerns about consumer fuel spending. Energy costs are spreading beyond the energy sector into transport and retail margins.
Power infrastructure benefits from the same energy scarcity. Generac surged 33% in premarket trading on Thursday after agreeing to supply up to $8 billion of backup generators for Amazon's data centers. High energy costs and grid reliability concerns make backup power more valuable. The industrial sector is splitting between companies that consume fuel and companies that sell energy security.
The equity signal is bearish for crude in the near term. When producer stocks fall faster than the commodity, investors are betting the commodity follows. Energy's second day of underperformance on Thursday, as the rest of the market rallies, shows equity investors see more downside in oil than futures currently price. Reversing that requires a new supply shock.
The Diplomatic Calendar and Geopolitical Wildcards
Diplomacy is the largest single driver of crude's direction. President Trump is expected to meet Gulf leaders next Tuesday on the sidelines of the UN General Assembly in New York to discuss next steps in the war with Iran. He said Iran wants to make a deal and that the war will end soon because Iran cannot go on. Any credible ceasefire framework would remove the war premium from crude.
Iran is not signaling retreat. An Islamic Revolutionary Guard Corps spokesperson warned that if the United States attacks again, it will face a more decisive, broader and stronger response. Iran vowed to respond to a U.S. blockade by pushing more trade overland. Military chiefs from the United States, Israel and Arab states held secret talks in Germany, noting increased risk in the Strait of Hormuz and Bab al-Mandab.
The war has already reversed once. In June, President Trump announced a preliminary U.S.-Iran peace deal that sent oil prices tumbling. On June 18, the United States and Iran signed an agreement to end the war and reopen the Strait of Hormuz. By July 29, WTI rose more than 6% after President Trump said the U.S. would strike back at Iran following an attack on a military base in Jordan. A peace deal that collapses within six weeks shows how fragile any diplomatic breakthrough is.
Russia adds a second geopolitical front. Congress approved a bill giving the President new powers to impose additional 100% tariffs on the five biggest importers of Russian oil or natural gas, and the measure goes to his desk for signature. The U.S. House also voted to impose sanctions and tariffs over Russia's war in Ukraine. The Kremlin said new sanctions will make a Ukraine peace deal harder. President Trump said the Ukraine war is the one driving up diesel prices.
Tariffs on Russian oil buyers target China and India, the largest importers. Enforcement would force those buyers to reduce Russian purchases or face 100% tariffs on their exports to the United States. Reduced Russian flows would tighten global supply further, adding upside risk to crude. The measure has not been signed, and enforcement would take time.
Trade tensions add a demand-side risk. President Trump threatened heavy tariffs on the European Union over its move to grant Canada associate status, and U.S.-Mexico trade talks were pushed back a week. Broader trade conflict slows global growth and weighs on oil demand. The geopolitical calendar is dense, and nearly every event can move crude by several dollars.
Support Map: $100, $100.39 and $95.63
Three levels define crude's downside. The first is $100 on WTI. U.S. crude briefly dipped below that level on Thursday before recovering to $100.55. The round number carries psychological weight: crude broke above $100 for the first time since July during last week's rally. A daily close below $100 would signal that the relief trade has absorbed the entire September escalation premium above that line.
The second is $100.39, the low of Thursday's European-session range for October WTI. Monday's intraday low of $100.53 sits 14 cents above it. Two lows in the same zone within four sessions make $100.39 to $100.53 a support band. From today's price, $100.39 is a 0.2% decline. It is the level WTI must hold to keep the week's structure intact.
The third is $95.63 on Brent. That was Brent's settlement price on September 2, before the latest escalation in attacks on Gulf infrastructure. From today's $103.05, $95.63 is a 7.2% decline. A return to that level would erase the entire September war premium in Brent. The trigger would be the Saudi pipeline reaching half capacity on schedule, a diplomatic breakthrough at next week's UN meetings, and a halt in Houthi strikes.
The inventory and freight data argue against a fast collapse. U.S. stocks fell 640,000 barrels against a forecast build. Freight costs hit records. Shanghai crude traded at $129. Those conditions make a sustained move below $95.63 on Brent unlikely without a ceasefire, because physical buyers are still paying premiums to secure supply.
The macro backdrop supports lower prices. Record diesel prices are destroying demand in freight and airlines. The Fed and other central banks are tightening. A stronger dollar weighs on crude. If supply relief continues, demand weakness adds to the downside. That combination makes a test of $100 on WTI more likely than not in the coming sessions.
The support structure favors a test, not a collapse. WTI has already touched below $100 intraday. A daily close below $100 confirms the break. A hold above $100.39 through Friday's session and next Tuesday's Gulf meeting would show buyers defending the round number. The level that matters most is the daily close relative to $100.
Resistance Stack: $102.47, $104.95 and $105.83
The upside has three layers of resistance on WTI. The first is $102.47, Wednesday's settlement and the top of Thursday's European-session range. WTI trades $1.92 below it. A daily close above $102.47 would reverse Thursday's decline and signal that the relief trade has stalled. From today's price, $102.47 is a 1.9% gain.
The second is $104.95, Monday's intraday high for October WTI. That level capped the first leg of this week's spike before Tuesday's breakout. A move back above $104.95 would require a new supply headline, most likely a delay in the Saudi pipeline restart or another attack on Gulf shipping. From today's price, $104.95 is a 4.4% gain.
The third is $105.83, Tuesday's settlement and WTI's highest close since May 19. That level marks the peak of the war-premium spike. Reclaiming it would erase the entire Wednesday-Thursday decline and put WTI 5.3% above today's price. On Brent, the equivalent level is Tuesday's $108.75 settlement, 5.5% above today's $103.05.
Above those levels lies the extended risk zone. Brent in the $119 to $120 area has been flagged as an upside scenario if attacks on oil infrastructure escalate further or if the pipeline restart fails. From today's price, $120 Brent is a 16.4% gain. That move would require a major disruption: a successful strike on Hormuz shipping, a collapse in Saudi rerouting, or a full closure of Bab al-Mandab.
Each resistance level has a clear trigger. Reclaiming $102.47 needs only a pause in pipeline headlines and a strong demand data point. Breaking $104.95 needs a Saudi restart delay beyond this week. Clearing $105.83 needs a new attack on Gulf infrastructure or shipping. Reaching $120 Brent needs a regional escalation that the market has not priced.
The resistance stack is wider than the support structure. From today's WTI price, first resistance at $102.47 is 1.9% away and the week's high at $105.83 is 5.3% away. First support at $100 is 0.5% away. The tight distance to support and the wider distance to resistance favor a downside test first. The geopolitical risk above keeps that test from turning into a one-way decline.
Three Scenarios: Relief, Range and Escalation
The relief scenario targets $100 on WTI, then $95.63 on Brent. It requires the Saudi East-West pipeline to reach half capacity within days as promised, ship-to-ship transfers near Oman to hold at 2.7 million barrels per day or higher, and Houthi attacks to pause after China's request to Iran. A constructive outcome at next Tuesday's Gulf leaders meeting would accelerate the move. In that case, WTI closes below $100 by early next week and Brent tests $98, then $95.63 before the end of September. From today's Brent price, $95.63 is a 7.2% decline.
The range scenario is WTI between $100 and $105.83 through the October 27–28 Fed meeting. The pipeline restarts partially, but independent satellite assessments showing longer repairs keep traders cautious. Houthi strikes continue at a lower intensity. U.S. inventories draw modestly, freight costs stay elevated, and the Shanghai premium narrows slowly. This outcome reflects the tension between paper-market relief and physical-market tightness.
The escalation scenario targets $105.83 on WTI and $108.75 on Brent, then $120 on Brent. It requires the pipeline restart to slip past September, a successful attack on tankers in Hormuz or the Red Sea, or a breakdown in Gulf-Iran diplomacy. A Houthi move to close Bab al-Mandab would be the most severe trigger. From today's Brent price, $108.75 is a 5.5% gain and $120 is a 16.4% gain.
The probability weighting favors relief in the near term and range over the month. The market has already priced two days of relief headlines. The pipeline restart timeline and the Saudi rerouting volumes are concrete, measurable and moving in the right direction. The first test is $100 on WTI, and the relief scenario is most likely to reach it. Beyond $100, physical tightness and geopolitical risk slow further declines.
The Fed is the swing factor for demand. If crude breaks below $100 and inflation expectations fall, October hike odds could drop below 50%, supporting growth and eventually oil demand. If crude spikes back above $105.83, the Fed is more likely to hike in October, which slows the economy and caps the rally. Monetary policy now limits how far crude can move in either direction before demand responds.
The largest downside risk is a durable ceasefire. It would remove the war premium from both benchmarks and likely send Brent through $95.63 quickly. The largest upside risk is an attack that closes Bab al-Mandab while the East-West pipeline is still impaired. That scenario would cut both Saudi export routes at once. Crude at $100.55 on WTI and $103.05 on Brent is priced for neither.
Oil Price Forecast Verdict: Bearish Tilt Toward $100, Invalidated Above $102.47
WTI enters Friday at $100.55, down 1.8% on the day, after briefly trading below $100. Brent trades at $103.05, down 2.6%. In three sessions crude spiked to its highest close since May 19, with WTI at $105.83 and Brent at $108.75, then reversed as Saudi Arabia outlined a pipeline restart and rerouted crude through Hormuz. WTI has lost 5.0% from Tuesday's close and Brent 5.2%, but U.S. crude remains up 17% for September.
The case for lower prices is concrete. Saudi Arabia is aiming to restore half of its East-West pipeline capacity within days and full operations within six weeks. Ship-to-ship transfers in the Gulf of Oman have risen to 2.7 million barrels per day from 1.5 million in August. China has asked Iran to help stop Houthi attacks. The U.S. Energy Secretary called the outage a brief interruption measured in days. Energy stocks are falling faster than crude, and record diesel prices are destroying demand in freight and airlines.
The case against a collapse is equally concrete. U.S. crude inventories fell 640,000 barrels to 423.4 million against a forecast 7.1 million-barrel build. Freight costs hit a record $44.8 million for a U.S. Gulf-to-China supertanker. Shanghai crude traded at $129 per barrel. The Houthis now hold territory near Bab al-Mandab, threatening the Red Sea route the pipeline feeds. Satellite images show significant pumping station damage that could extend repairs beyond the Saudi timeline.
The forecast is a bearish tilt with a defined line. WTI support sits at $100, then $100.39, with Brent's $95.63 pre-escalation level as the extended target. Resistance holds at $102.47, $104.95 and the $105.83 weekly high on WTI, with $108.75 on Brent. A daily close above $102.47 invalidates the bearish tilt and puts $105.83 back in play.
The trigger is the pipeline. Confirmation of half-capacity restart this week, combined with steady Hormuz transfers, confirms a daily close below $100 on WTI and opens a move toward $95.63 on Brent. A restart delay beyond September or a successful attack on Gulf or Red Sea shipping sends WTI back through $102.47 toward $105.83.
Verdict: bearish bias below $102.47 on WTI, targeting a daily close below $100 near term and $95.63 on Brent on confirmed pipeline restart, with the forecast invalidated on a daily close above $102.47.